
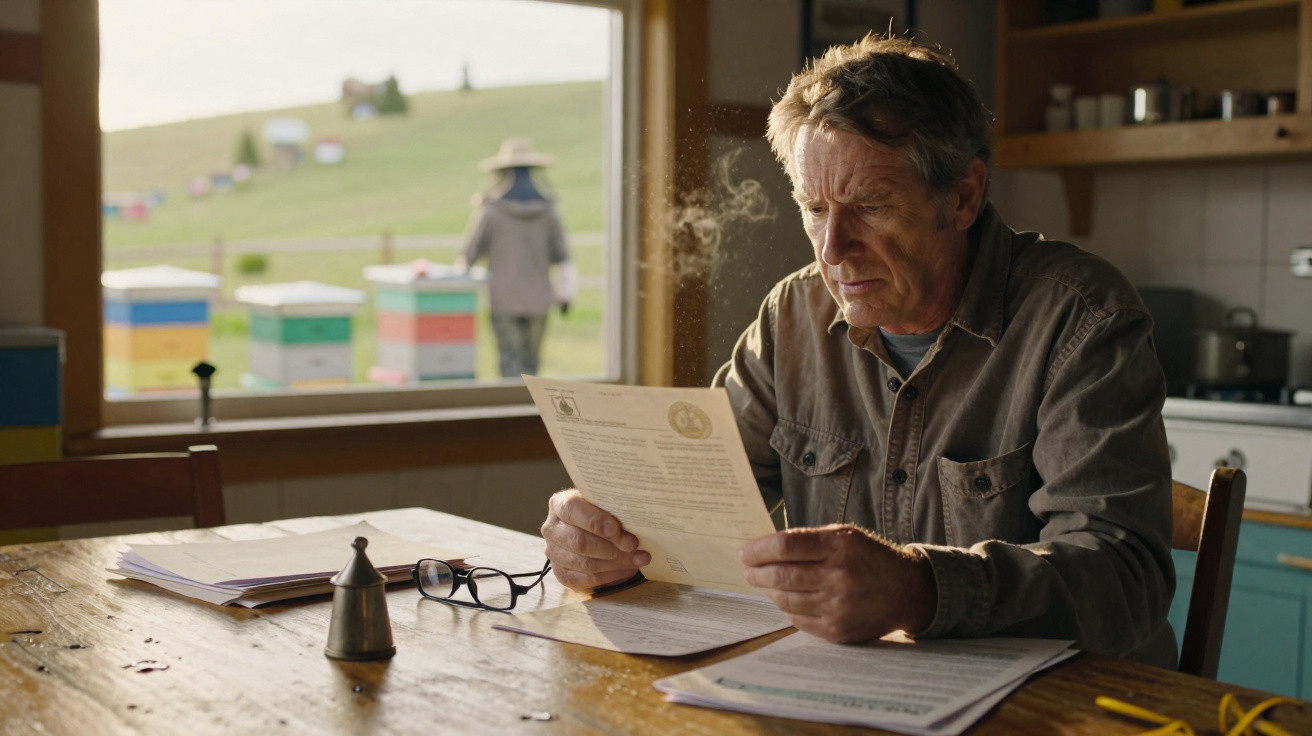
The morning the letter came, Jean* assumed there had been an error. A plain brown envelope from the tax office had slipped through the letterbox of his modest home on the village outskirts. He put on his spectacles, sat down at the kitchen table and laid the documents beside his coffee. Within three minutes, his hands were trembling.
It was an agricultural tax bill for several thousand euros. The charge was due because his land had been classified as being “exploited for professional activity.” Exploited by whom? The beekeeper who had kept hives in Jean’s fields without charge, supposedly “just to help the bees” as Jean moved towards retirement.
“I’m not making a cent from this,” he said quietly, looking at the sum he owed.
Beyond the house, the drone of the hives blended with the traffic at midday. Indoors, a different sort of buzzing had begun.
When good deeds collide with tax law
On the face of it, the arrangement had an almost idyllic quality. An older landowner with no intention of working his remaining fields. A young, enthusiastic beekeeper looking for a peaceful site for hives, clear of pesticides and heavy traffic. They simply shook hands, with no written agreement, only a shared understanding: use the land, support nature, and everybody benefits.
The months went by. Honey was produced. Images of amber jars and busy bees appeared on social media. Villagers applauded the scheme, pleased to see rural life “revived”. Then the tax notice arrived. The state had a far less romantic description of what was happening.
Jean’s experience is far from unique. Throughout rural Europe, growing numbers of retired people allow beekeepers, small-scale market gardeners and even horse owners to use their fields. There is no rent and no formal lease. It may be a friendly exchange at the market, a conversation by the roadside, or a swap for eggs or a jar of honey. Yet, one year, the tax authority may reclassify the land as being used for professional activity.
An owner who believed they were merely “helping out” can then face agricultural tax, a land revaluation and, in some cases, backdated charges. Meanwhile, the beekeeper continues selling honey at fairs and online. The owner is the one left disputing the matter with a tax inspector by phone.
The principle behind this is straightforward. Where land supports a professional or commercial operation, the authorities may regard it as an agricultural asset, even when the owner receives no income. That is the distressing part for people such as Jean. He believed he had lent the land, kept it in use and encouraged biodiversity. The tax office saw a regular, organised economic activity taking place on his property.
This is also where villages become divided. Some neighbours believe the beekeeper is exploiting Jean’s generosity. Others take the view that the rules are plain: landowners must protect themselves.
The thin line between kindness and naivety
One uncomplicated, rather unglamorous step could have saved Jean considerable worry: a brief written agreement. It could have stated clearly who was responsible for what, who earned what and which obligations each person accepted. There would have been no need for anything elaborate: a few lines signed by both parties, perhaps setting out a token rent, the arrangement’s duration and confirmation that the landowner had no role in the professional activity.
Many rural solicitors offer the same advice: treat even the warmest informal arrangement as a proper contract. That does not destroy trust; it safeguards it. The document need not run to ten pages. It simply needs to exist.
The usual error is deeply human. You meet someone passionate about bees, horses or vegetables. Your land matters to you, and you want it to remain alive rather than lie abandoned. So you say, “Go on, put your hives there, it’s fine, I’m not using it anyway.” There is no invoice, contract or awkward discussion-just a handshake and a sense of doing something good.
Then, months later, you are holding a tax demand while the beekeeper says, “Oh, I didn’t know it would affect you.” Those words can sting more than the bill itself. Not necessarily because anyone acted in bad faith, but because it suddenly becomes clear that nobody ever addressed the tedious practical issues.
That is when tempers flare in the village pub and on local Facebook groups. Some describe the beekeeper as a profiteer benefiting from an elderly man’s goodwill. Others say Jean should have checked the rules and behaved like an adult rather than a child in an adult world.
“I just wanted to help the bees and keep the land alive. I never imagined the state would count their honey as my activity,” Jean says, eyes fixed on the paperwork spread across his table.
- Clarify the status of the activity on your land: hobby, semi-professional, or full business.
- Ask a local tax adviser or farmers’ union to review your individual circumstances.
- Record expectations in writing, including when dealing with relatives and friends.
- Review your land’s tax classification before consenting to any new activity.
- Discuss money frankly, even where “it’s just a few hives”.
A quiet drama that says a lot about rural life today
Jean and the beekeeper’s story is not really about bees. It concerns the conflict between goodwill and bureaucracy, oral traditions and digital forms, a handshake and a PDF. For many landowners approaching retirement, land represents memory and identity-almost another member of the family. For young, small-scale producers, it is a means of survival: a plot where a precarious business can establish itself.
Somewhere between those positions, tax rules move forward like a slow, uncaring tide. People either adjust or go under.
Most of us recognise the moment when generosity comes first and administrative questions are left until later, if they are considered at all. In truth, hardly anyone reads every land-use rule before agreeing to help a neighbour. The hard fact is that the law is unconcerned with good intentions. It looks at who owns the ground, whose name appears on the cadastral map and who can be pursued for unpaid charges.
To some, that seems like a quiet penalty for being kind. To others, it is simply part of property ownership in a world where almost nothing remains entirely “informal”.
Some names have been changed.
Stories of this kind spread quickly. At the bakery, people murmur, “Did you hear about Jean and his bees?” Online, readers share similar accounts: a horse paddock that led to a tax reassessment; a small vegetable plot lent to a young farmer that became a legal problem; an orchard made available to a cider maker for “just a season” that continued well beyond it.
The land hasn’t changed, but the way we use it has. Every jar of honey, crate of vegetables and bale of hay now stands where law, money and trust meet. The way communities renegotiate these unwritten arrangements will quietly influence thousands of retirements during the next decade.
| Key point | Detail | Value for the reader |
|---|---|---|
| Hidden tax risk | Allowing land to be used for hives or small-scale farming may trigger agricultural tax, even where no income is received | Helps readers identify the risk before they say “yes” |
| Written agreements | Straightforward contracts set out responsibilities and protect both the owner and the user | Provides a practical, inexpensive means of avoiding unpleasant surprises |
| Talk about money | Open discussion of revenue, status and duration can prevent resentment and disputes | Protects relationships while acknowledging legal reality |
FAQ:
Question 1: Can I really be taxed if I’m not earning anything from the beekeeper on my land?
Yes. Tax authorities often consider how the land is used rather than your own personal profit. Where professional activity occurs there, the land may be reclassified and taxed accordingly, even if you do not earn a euro.Question 2: Would a symbolic rent of a few euros change anything?
Sometimes, charging a small, clearly specified rent and setting out a basic lease can help demonstrate that you are a landlord rather than an unspoken business partner. A local adviser can say whether this is appropriate for your circumstances and local law.Question 3: Is a verbal agreement with a beekeeper or farmer ever enough?
Socially, perhaps. Legally, it is vulnerable. Without written evidence, responsibilities remain unclear, while you retain most of the ownership risk and little control over the activity taking place on your land.Question 4: What should a simple land-use agreement include?
The names and details of both parties, a description of the plot, the duration, the permitted activity, responsibility for taxes and insurance, and what happens if either person wishes to end the arrangement.Question 5: How can I protect myself without ruining the relationship?
Say that you value both the project and the person involved, but need clarity for tax and inheritance purposes. Suggesting that you meet together with a notary, farmers’ union or legal adviser often reassures everyone and preserves trust.
Comments
No comments yet. Be the first to comment!
Leave a Comment