
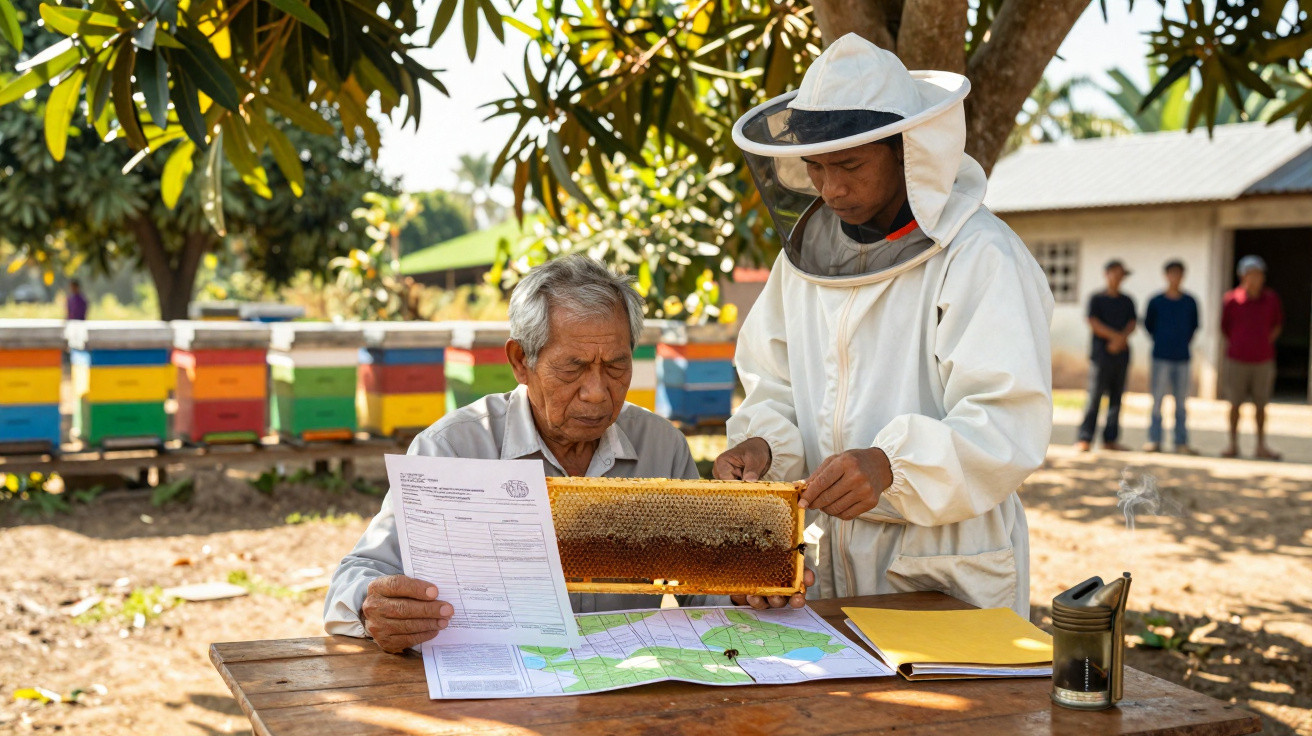
At the edge of a parched field in Negros Occidental, a retired state-school teacher stands among lines of buzzing beehives. Without his glasses, he struggles to make out the paper in his hands. It is packed with legal jargon, bears three stamps and carries the chilly formality only a government office seems able to produce. It is a tax demand - an enormous one. Agricultural land tax, fines and surcharges, all charged against property he no longer truly thinks of as his.
He gave the fields to a young beekeeper who reminded him of the pupils he once taught: intelligent, optimistic and desperate for an opportunity.
Yet the authorities are now demanding payment for land on which, in his words, “I haven’t earned a single peso from those hives.”
To some, that is fair. To others, it is robbery in broad daylight.
When generosity becomes a land tax nightmare
The retired teacher, known to neighbours simply as “Sir Tony”, believed he was doing something worthwhile with his final substantial asset: several hectares of farmland inherited from his parents. He has no children, relies on a pension that scarcely lasts the month, and wanted the land to be tended rather than sold to a resort developer. So when a young beekeeper came to him with a proposal for a modest apiary, he felt compelled to help.
They prepared a straightforward deed of donation. The hives were delivered, and the bees began their work. Then a tax notice arrived at his home like a blow.
Neighbours recount the episode in pieces. One remembers municipal assessor’s office staff arriving to find the “registered landowner”. Another saw Sir Tony, still wearing his slippers, trailing the officials as they photographed the hives in the fierce midday heat.
In the records, the land’s valuation changed as soon as its agricultural purpose was classified as “commercial”. The donated field was labelled productive farmland containing a business, setting off a different calculation for real property tax and agricultural charges. By the time the notice reached him, the sum was devastating - enough to consume years of his modest public-sector pension. The beekeeper, who was still trying to expand and sell honey in local markets, had no money to spare either.
The matter soon travelled well beyond their barangay. Images of the tax demand and brief videos of the elderly man discussing his “no-income hives” spread across Facebook and TikTok. The comments became a battlefield. One group insisted: rules are rules, taxes fund schools and roads, sentiment cannot override the law. The other saw a devoted public servant being penalised for generosity, while a young farmer-entrepreneur was caught in a system seemingly built for major agribusinesses rather than precarious, hopeful ventures.
Behind the uproar sits a larger question: when the state applies the same treatment to every field and every hive, who is stung most severely?
The hidden dangers in “good deals” for rural land
For many Filipinos, land still changes hands in the “old way”: with a handshake, a promise or a basic document printed in town that nobody has properly read. This is how many generous transfers, particularly in rural communities, take place quietly. A retired family member gives farmland to a younger cousin. A neighbour permits a tenant to “take over” a parcel in return for looking after it. On the face of it, the arrangement feels personal, humane and even admirable.
But each of these gestures may activate provisions in the tax code. Good intentions rarely matter to tax rules.
In situations such as Sir Tony’s, the land donation was not accompanied by a clear, prompt update to tax records or a detailed arrangement over who would meet future liabilities. It is a familiar oversight. Many small landowners assume the process ends once a notary public has stamped the deed. In reality, that is when the Bureau of Internal Revenue, the municipal assessor and the treasurer’s office become involved, each with separate forms, deadlines and penalties.
Then comes the complication. Land may initially be idle or of limited value. Once even a small enterprise appears - a few hives, a vegetable plot selling through a co-operative or several fruit trees harvested for market - a new valuation may apply. What seemed an innocent, almost symbolic transfer can quietly become a taxable transaction.
The wider trend is difficult to overlook. Across the Philippines, retired professionals, widows and older farmers are finding that their “simple arrangements” are actually complicated taxable transactions written in invisible ink. This is where the national argument divides. Those who say “rules are rules” maintain that tax should be neutral: identical land, identical use and identical levy, whoever owns it.
The other side focuses on everyday reality. They see retired teachers who spent decades in poorly paid public service now pursued for money they never actually received. They see young beekeepers and small farmers who are encouraged to innovate and “go agripreneur”, only to face regulatory costs designed for companies rather than two people trying to turn sunshine and flowers into honey. Let’s be honest: nobody really reads the fine print before putting bees on a field.
How to avoid being stung by a “kind” land transfer
One quiet lesson from this story is clear: generosity needs paperwork that works in ordinary life, not merely in a solicitor’s office. Anyone considering donating farmland - whether for bees, rice or a small cacao plot - should pause before transferring the title. The first sensible step is hardly romantic: visit the municipal hall and ask directly, “If I donate this land, who pays what, and when?”
A brief, mildly uncomfortable discussion with the assessor’s office could avert years of financial distress.
Many assume that, because land is being “gifted”, the state will treat them gently. That is a painful misconception. A donation may bring donor’s tax, capital gains tax, revised real property tax liabilities and even penalties for earlier under-declarations. The most frequent error is acting too quickly out of emotion - trying to “do something good” before age, illness or family conflict intervenes. Documents are therefore signed without understanding the consequences.
Another risk is failing to define anything. Who will formally be responsible for future land taxes? Will the young farmer repay the donor over time? What happens if the project does not succeed? Without firm answers, relationships deteriorate, families divide, barangays gossip and people such as Sir Tony are left caught between pride and embarrassment.
At the centre of such cases is a quiet need for people who can put legal and tax language into everyday terms. That may be a lawyer, a farmers’ co-operative, a progressive parish priest or a local NGO working on land rights.
“I thought I was just giving a chance, not signing up for debt,” one retired landowner in Iloilo shared in a community meeting on land reform. “If someone had just explained the taxes, we would have done it differently.”
- Confirm the land’s real property tax status before making any donation.
- Record who will pay each tax after the transfer, using a realistic timetable.
- Ask the LGU whether small-scale agricultural use could qualify for relief or reclassification.
- Get support from farmer organisations or legal-aid desks familiar with agrarian rules.
- Reassess the arrangement after the first harvest, rather than five years later when penalties have accumulated.
A sting that exposes what the countryside truly values
Accounts like Sir Tony’s spread quickly because they touch a nerve. People recognise their parents, their titos and titas, and their own modest hopes of retiring on a small plot with fruit trees and chickens. They also recognise the narrow divide between generosity and exploitation - whether by individuals, systems or a tax code written far from the dirt tracks and carabaos of their youth.
There is also increasing anxiety about the type of farming the country is quietly choosing to support. Are policies intended to foster small local beekeepers, organic growers, seed keepers and co-operatives? Or do they better serve industrial plantations that can absorb unexpected demands without difficulty? The tension between those two models is written into every tax notice that arrives in a plastic envelope, demanding payment from someone who never sold a single bottle of honey.
Here, the argument is no longer theoretical. One side holds on to the reassurance of uniform rules. The other asks whether justice can ignore context and still deserve that name. Between them is a retired teacher on a dusty track, watching his hives and wondering whether he should simply have sold the land to the highest bidder and avoided the trouble.
For readers scrolling through their phones, perhaps on a bus or during a lunch break, the question returns quietly: if you owned a piece of land and a young dreamer asked for an opportunity, what sort of arrangement would you be willing to offer, knowing what you know now?
| Key point | Detail | Value for the reader |
|---|---|---|
| Hidden tax triggers | Donations and small farm ventures can alter land classification and tax rates overnight. | Helps you predict genuine costs before giving or accepting farmland. |
| Need for clear agreements | Written terms identifying who pays current and future taxes can safeguard relationships. | Limits disputes and unexpected bills between donors and young farmers. |
| Seek local guidance | LGUs, co-operatives and legal-aid services can explain the rules in plain language. | Provides practical allies so you do not face rural bureaucracy alone. |
FAQ:
- Question 1 Can a land donor be held liable for taxes even after signing a deed of donation?
- Answer 1 Yes. Until the transfer has been completely processed, registered and updated with the assessor and BIR, the original owner often remains on record and may still be pursued for unpaid real property taxes or earlier obligations.
- Question 2 Does putting beehives or a small farm on land always increase taxes?
- Answer 2 Not always, but it may. Once land is regarded as commercially productive, assessors can revalue it, affecting annual tax liabilities, particularly if it is no longer considered idle or solely residential.
- Question 3 Can small farmers or beekeepers get tax relief for low-income operations?
- Answer 3 Some LGUs provide lower rates or incentives for small-scale agriculture, but these schemes vary and are often poorly publicised. You generally need to apply rather than simply hope.
- Question 4 What basic documents should be reviewed before donating farmland?
- Answer 4 At a minimum: the land title, the latest tax declaration, evidence of tax payments and the draft deed of donation. A brief consultation with the local assessor or a legal-aid group can identify hidden problems.
- Question 5 Is it safer to lease land to a young farmer instead of donating it?
- Answer 5 Leasing can be more straightforward because ownership remains with the original landholder while use is governed by contract. Even so, both parties should set out rent, tax duties and the term clearly, so that nobody later feels trapped or exploited.
Comments
No comments yet. Be the first to comment!
Leave a Comment