
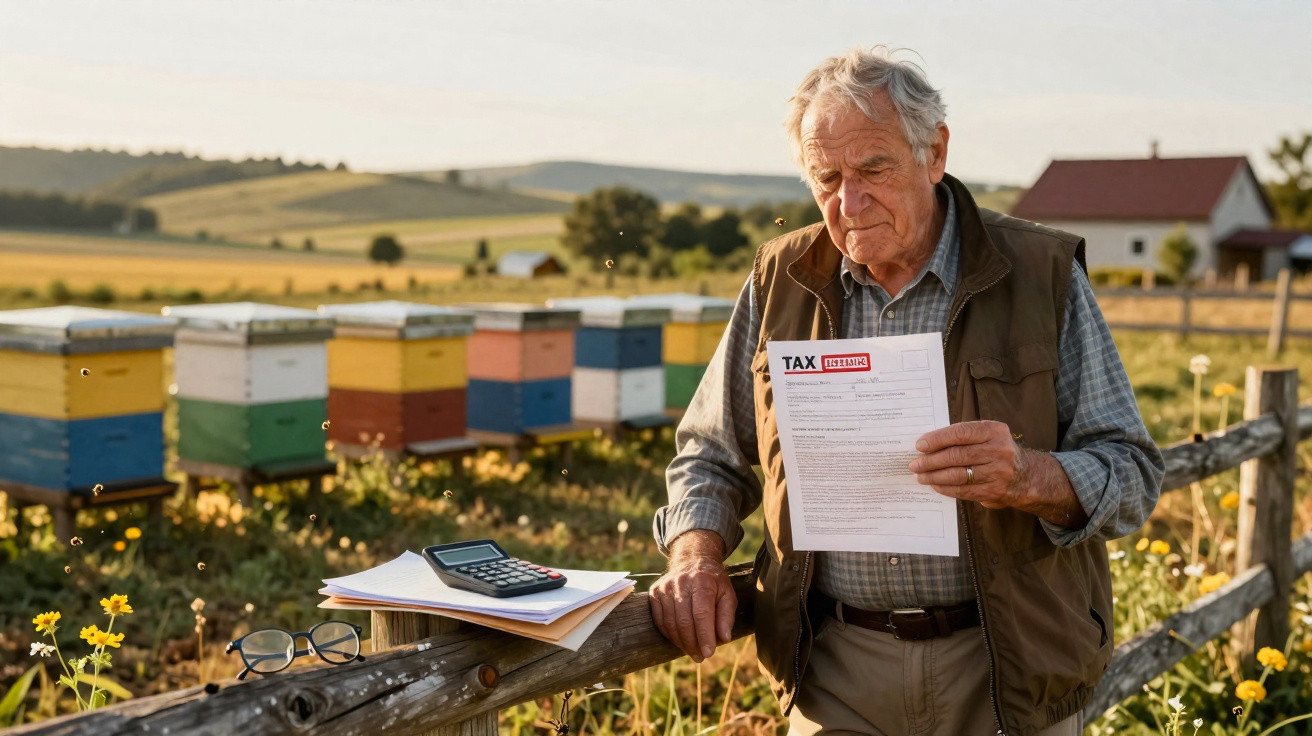
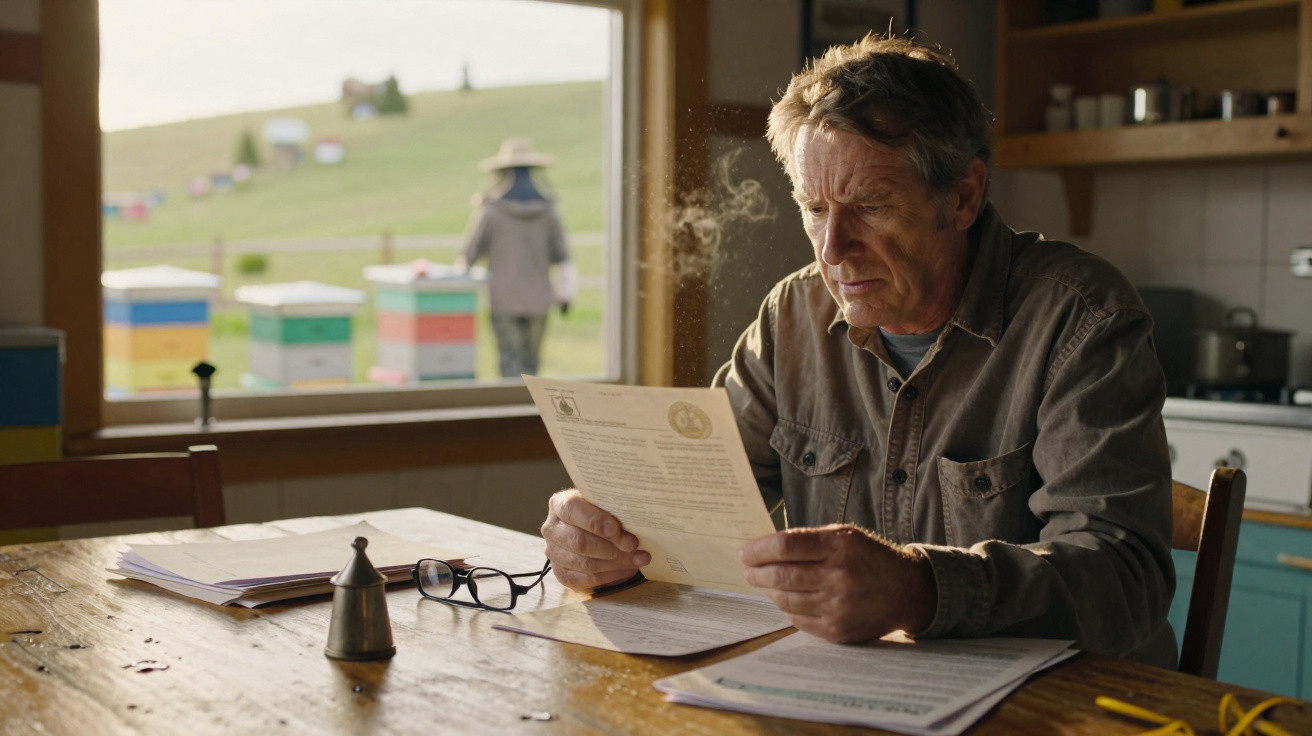
The letter came through the door on a Tuesday, one of those grey mornings when the kettle seems to take longer to boil and the house feels too large. Margaret, 73, made her way to the hall, her glasses sliding down her nose, and opened the brown envelope more from routine than interest. The tax office. Again.
She checked the figures twice, then a third time. Agricultural land tax. Thousands. It related to the small field she had allowed a young beekeeper to use free of charge, so his hives would have somewhere safe and the wildflowers would not be bulldozed.
Her tea sat untouched and went cold on the worktop.
There was no rent and no income. Only bees, wild clover and a handshake between two people doing their best to stay afloat.
It appeared the state had arrived late - and handed her the bill.
When generosity triggers the taxman
A low-level anger is growing among retired people with a small piece of land and a generous instinct. The same situation is playing out in villages and suburbs alike. A pensioner, seeing their savings diminish, chooses not to sell a modest plot but to let a small farmer, beekeeper or market gardener use it, often without charge.
There are no contracts, no money changing hands and no ambitious business scheme. There is simply a belief that unused land ought to help feed somebody, or at least provide space for a few hives.
Then the tax demand arrives.
Margaret’s field is small: under a hectare behind her cottage, edged by brambles and an old stone wall that has partly sunk into the ground. Two summers earlier, Tom - a beekeeper in his thirties with a rusty van and weary eyes - had knocked at her door, and she immediately recognised something familiar in him.
He was trying to create something honest out of almost nothing.
She agreed while standing in the doorway, drying her hands on her apron. There would be no rent. “Plant whatever flowers they like,” she said, gesturing towards the humming corner where wild thyme clung stubbornly to the earth. For two years, she had received jars of honey and the quiet comfort of knowing that her land was serving a worthwhile purpose.
Then came the tax bill, which described her as though she ran a full-scale agricultural operation.
At the heart of the problem is a legal minefield that most people never examine until it blows up beneath them. Tax rules commonly categorise land not according to the income it generates, but according to its recorded use. When land is deemed to be “in agricultural use”, it may set off a chain of requirements: declarations, local charges and agricultural-rate land taxes founded on the assumption that somebody, somewhere, is making a profit.
The system seldom differentiates between a retired woman lending a field without charge and a corporate farm renting hundreds of hectares.
It was built around large sums, orderly paperwork and official leases - not a pensioner and a beekeeper drinking tea at the kitchen table and drafting a basic arrangement on the back of an envelope.
The quiet ways to protect yourself without losing your soul
The first, if slightly unromantic, measure is to put neighbourly goodwill into terms the tax office can understand. That means paperwork. Draw up a brief written agreement clearly confirming that there is no rent, no income and no commercial partnership, only permission to use the land while the owner remains outside farming activity.
It need only be one page.
Include dates and signatures, along with a straightforward statement that the landowner receives no agricultural income whatsoever. It may feel impersonal beside a handshake, but this small administrative step can be the only protection separating a retiree from an unforeseen demand. Where possible, send a basic notification to the local authorities and retain a copy of any response, even if it merely acknowledges receipt.
The next step is less obvious but equally important: have an open discussion before anything is put on the land. Hives, polytunnels, sheds and feed storage can all alter how a plot is classified on official maps or within administrative databases. Many small farmers do not appreciate that improvements to their production can quietly place the landowner in a different legal category.
Ask direct questions. Who will register the activity? In whose name? Which address will appear on any agricultural registration?
We have all had that moment of agreeing because we do not want to seem awkward. But this is exactly how many retirees end up being seen by the state as the “owner” of an agricultural activity despite never receiving a penny.
The most serious mistake is assuming that “since I earn nothing, I owe nothing.”
The taxman is less concerned with good intentions than with how a record appears on a screen.
“From the system’s perspective, a free loan of land can look exactly like a commercial lease if nobody bothers to spell out the difference,” explains one rural tax lawyer. “Once the land is coded as agricultural and linked to a name, you can spend months trying to prove you aren’t secretly running a farm from your living room.”
- Ask the person using the land to accept full responsibility for agricultural registrations in their own name and business.
- Retain records: the agreement, all correspondence and evidence that you receive no income or subsidies connected with the land.
- Check your plot’s classification on official land maps, and seek corrections if it has been incorrectly recorded as a professional holding.
- Consider the effect on local property taxes before agreeing, rather than a year later when the bill has quietly grown teeth.
- Seek brief, one-off legal advice; an hour of clarity now may prevent years of letters and appeals.
When the law meets basic fairness
The entire episode raises an uneasy question: has the state begun to penalise generosity more severely than greed? A major investor who buys land, leaves it vacant and waits for values to rise can often remain relatively unaffected. Their file appears straightforward: no complicated shared use, no unclear activity and no community projects at the edges. Just ownership.
By contrast, the retired person who helps a young farmer or opens a gate for bee colonies can suddenly be placed in a category for which the law was never thoughtfully designed. The system records use rather than motive.
Let us be honest: hardly anyone reads every tax guideline before allowing a beekeeper to place a few hives in a back field.
| Key point | Detail | Value for the reader |
|---|---|---|
| Clarify roles in writing | A simple signed agreement confirming that the landowner has no income and undertakes no farming activity | Lowers the risk of being treated as an undeclared farmer for tax purposes |
| Check land classification | Confirm how your plot appears on official maps and in tax records | Identifies mistakes early, before they lead to higher or unsuitable taxes |
| Share responsibility fairly | The small farmer or beekeeper registers their activity in their own name | Protects retirees while enabling ethical local food and pollination projects to flourish |
FAQ:
- Question 1 Can I lend my land for free without paying extra taxes?
- Question 2 Do I need a formal contract if I trust the person using my land?
- Question 3 Why am I taxed as if I’m farming when I receive no income at all?
- Question 4 What practical steps can I take if I’ve already received a tax bill like this?
- Question 5 Is there any way to help young farmers and beekeepers without putting my pension at risk?
Comments
No comments yet. Be the first to comment!
Leave a Comment