
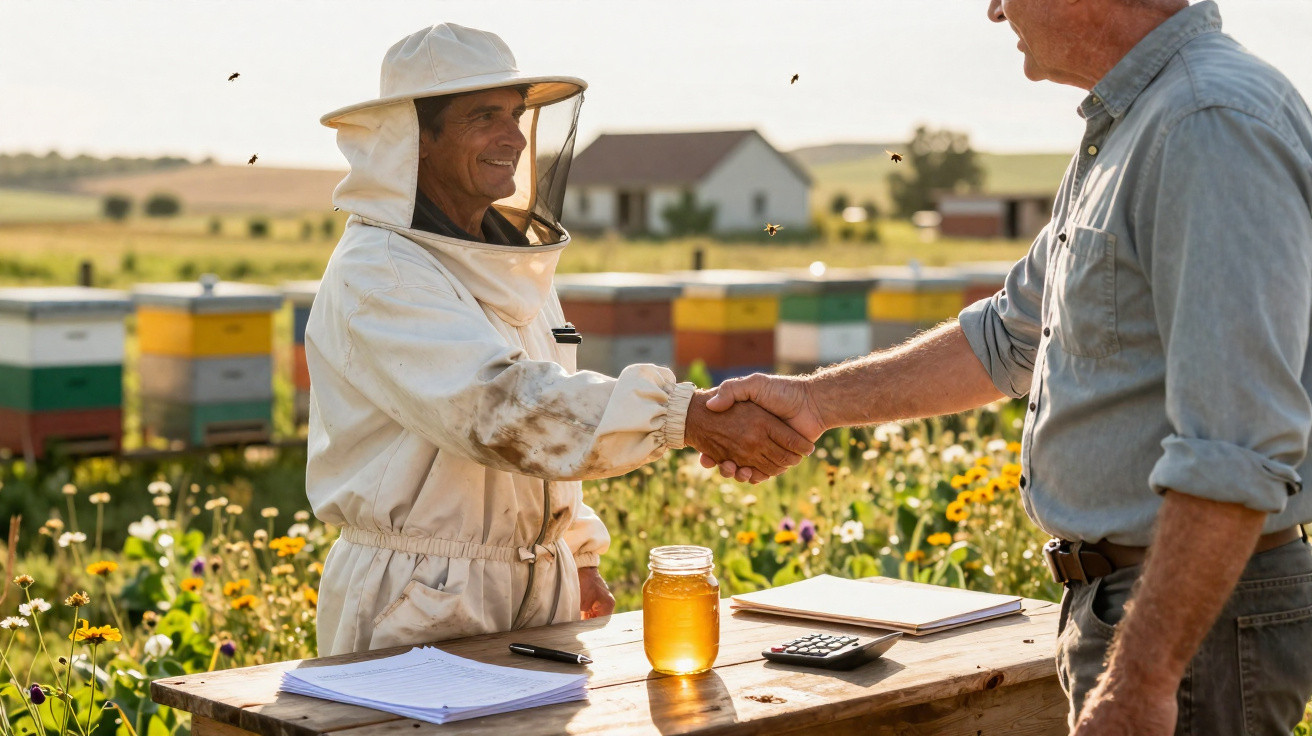
The first time I noticed the sign, it had been fixed at an angle to a fence post: “Honey from hives on this farm.” On a folding table sat rows of jars, their golden contents catching the late-afternoon sun. Wearing a weathered cap, a man flagged down cars travelling along the gravel track and had sold everything before sunset. He was the beekeeper. Several metres behind him stood the silent farmhouse, its blinds partly drawn and its owner nowhere to be seen.
Over coffee in town later, I discovered something that stayed with me: the beekeeper takes the money from every jar. The landowner, whose field gives the hives a sunny home, receives… a reduced tax bill. Sometimes, though, they also inherit a major problem when the taxman calls.
At first, it seems like a sweet arrangement.
That is, until you look at the small print.
When honey meets the tax office: the quiet deal on rural land
Once you know what to look for, you will spot them across almost any rural landscape: slender white boxes positioned beside fences, at the edge of trees or behind barns. They are beehives. They appear harmless, even ornamental, but many conceal a low-key agreement between two people who may barely see one another annually.
One party is the beekeeper, who requires somewhere to place their hives. The other is a landowner hoping to secure agricultural or open-space tax breaks. Their arrangement is straightforward: “You put your bees here, I get my ag status, we both win.”
Until the demand arrives.
Typically, it unfolds like this. A small landowner purchases several acres on the edge of town. Their taxes are steep because the property is categorised as residential or speculative land. A neighbour tells them, “Get some bees on it and you can qualify for an agricultural valuation. Cuts your property tax way down.”
They then contact a nearby beekeeper, who brings in 10, 20 or perhaps 40 hives. The honey is extracted, labelled and sold at farmers' markets or online. Little else happens to the land. Officially, however, it is now considered to be “in agricultural use”. The owner's tax bill falls sharply.
Three years afterwards, the county conducts a reassessment. Perhaps the rules have been amended, the land has not been used sufficiently, or the documentation fails to match up. All at once, the landowner is confronted with back taxes, penalties and a deeply unpleasant feeling in the pit of their stomach. The beekeeper? Their hives have already been relocated to another field.
This unusual connection between bees and tax codes has become, simultaneously, a loophole, a lifeline and an ethical puzzle. Whether it is Texas “bee ag exemptions” or open-space valuations in other states, the broad principle is identical: agricultural land use means lower tax. Bees “count” as agriculture, despite the beekeeper potentially being entirely separate from the landowner.
At one level, the rationale is sound. Pollinators are in crisis, while ground occupied by hives is, technically, being used. The financial reality, however, is uneven. The beekeeper receives a free or inexpensive site and retains all honey income. The landowner carries the legal obligation, the danger of a challenge from the tax office and, frequently, the expense of fencing, access and even liability if somebody is stung on the site.
Is that equitable, or merely the price of taking part in the rural tax game?
How to keep the honey sweet and the tax bill sane
Landowners attracted by the promise of “get bees, slash taxes” should pause before acting. The first practical call should not be to a beekeeper, but to the county or local tax authority. Request written guidance on agricultural or open-space valuation as it applies to beekeeping.
In most areas, thresholds apply: a set hive number per acre, a minimum plot size or a minimum period of continuous use. Get those figures in black and white. Not as a story your neighbour told you over the fence.
Only after establishing the criteria should you begin discussing where the hives could realistically be located.
There is a human weakness at the centre of this situation: the handshake agreement. It feels neighbourly, familiar and traditional. You meet a beekeeper locally; they appear trustworthy and assure you, “Don’t worry, I do this all the time, you’ll be fine.” Naturally, you want to trust them. Most of us recognise that moment when a confident person makes a complex system appear effortlessly straightforward.
That is the point at which difficulties begin. Who bears the cost if the hives are vandalised? Who is liable when a worker is stung on your property? Who maintains the records the tax office may demand, including hive totals, harvest dates, photographs and invoices? Realistically, no one manages this every day without fail. Leave the details unclear and they will remain unclear-until an envelope from the tax assessor arrives through your letterbox.
The less glamorous solution is to handle a “bee-for-tax” arrangement as an authentic commercial relationship rather than an informal favour among neighbours. At a minimum, that requires three practical actions:
Put it in writing. “If the tax office revokes or denies my agricultural valuation linked to these hives, who covers what?” is not a rude question. It’s adult life.
- Set out in a straightforward written agreement who owns the hives, honey and equipment.
- Specify who will retain tax-file records, including hive photographs, dates, hive counts and inspection notes.
- Decide how to respond if regulations change during the arrangement: by sharing expenses, dividing risk or ending the agreement.
- Review insurance cover: does your liability policy apply to visitors, vehicles and hive-related stings?
- Arrange an annual review before filing any tax documents, rather than dealing with matters afterwards.
So who really wins: the beekeeper or the landowner?
Remove the romance of jars and wildflowers, and the beekeeping-for-tax exchange exposes a broader issue: who carries which burden in rural economies? The beekeeper contributes a living asset-colonies needing room, forage and relative peace. The landowner contributes the land itself, along with the legal status recognised by the tax office. Each party benefits from the other. That is not automatically exploitative, but it must be properly balanced.
Some people consider the arrangement unjust to landowners, who may be vulnerable to penalties far greater than the savings achieved. Others argue that taxpayers lose out when high-value land receives tax relief despite minimal farming activity. Defenders, meanwhile, observe that many small owners would otherwise have to sell, and many beekeepers would have nowhere to put their hives.
Perhaps fairness does not mean dividing honey proceeds equally. Instead, it may mean distributing risk in a way that is candid and reasonable. Beekeepers might pay modest rent or offer some honey when the tax advantage is substantial. Landowners, equally, might acknowledge that they are receiving a genuine gain: thousands removed from a bill in return for accepting a few boxes in a rear pasture.
For some people, the exchange remains unbalanced. For others, it is a quiet agreement that keeps land accessible, bees active and both sides afloat in a system that rarely shows much concern for either.
The greater inequity may exist a level above them, within tax codes that reward the appearance of agriculture without truly assessing ecological value or real agricultural work. Unless those rules change, the question “Who gets the honey and who gets the bill?” will continue to resonate in rural kitchens and county offices.
What remains is a discussion that seldom takes place in person. Buying a jar labelled “local honey from hives on this farm” does more than support a beekeeper. Without realising it, you become part of a fragile three-way relationship involving bees, land and law. Some of these arrangements are open and equitable; others are held together by optimism and spoken assurances.
As a landowner, you may be drawn to the simple version: one phone call, a few hives and a large tax reduction. As a beekeeper, you may believe your presence alone is doing the landowner a favour. Both views can be valid, yet still fall short.
There is scope for better practice: clearer contracts, jointly maintained records, a small amount of rent or honey exchanged, and a joint visit to the tax office rather than separate accounts. Rural life has long depended on such understated arrangements. The issue now is whether to move them towards shared accountability, or continue to act as if the system offers “free honey for everyone” when somebody invariably pays more than anticipated.
| Key point | Detail | Value for the reader |
|---|---|---|
| Understand the rules first | Obtain written criteria from your tax authority on agricultural valuation based on beekeeping | Lowers the likelihood of unexpected back taxes and penalties |
| Formalise the bee deal | Use a simple written agreement covering ownership, records and risk-sharing | Safeguards both the landowner and beekeeper if problems arise |
| Share benefits and risks | Consider rent, a honey share or cost-sharing linked to the tax benefit | Supports a fairer and more sustainable long-term arrangement |
FAQ:
- Question 1 Can beehives on my land genuinely reduce my property taxes?
- Question 2 Who normally retains the honey profits in these agreements?
- Question 3 Which documents could the tax office request?
- Question 4 Should the beekeeper pay rent or provide the landowner with a share of the honey?
- Question 5 What is the most significant mistake landowners make with “bee exemptions”?
Comments
No comments yet. Be the first to comment!
Leave a Comment