
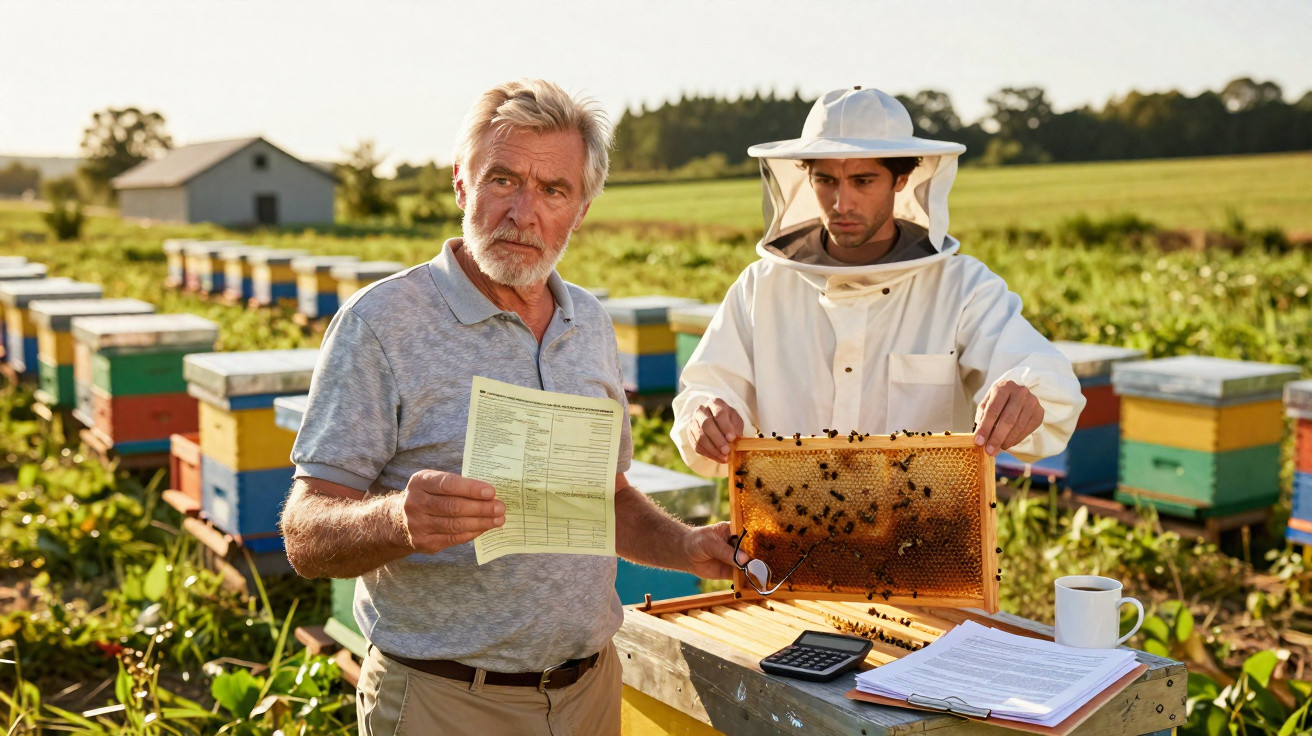
On a misty morning in March, with the horizon fading into a pale blur, Jean was taking his dog along the boundary fence when his phone began to vibrate. The number for the town hall appeared on the display. After a moment’s hesitation, he wiped his hand on his worn work trousers and answered. The caller sounded courteous, almost regretful: “About the land you lent to the beekeeper… there’s a tax issue.”
Jean stood still in the mud as his boots sank slightly further down. At 72, he is a former factory worker whose joints bear the marks of decades on shift, and he survives on a modest pension. He is not a farmer, sells nothing and does not “exploit” his 1.6-hectare plot. He simply allows a local beekeeper to keep several hives there, tucked quietly among brambles and walnut trees.
The town now wants him to pay a tax linked to farming because of that “activity”. The bees labour for nothing, the beekeeper “isn’t making a cent” so far, and the retired owner is the only person feeling the sting.
Somewhere between mutual support and freeloading, the boundary has been crossed.
When a kindness becomes a tax demand
From the road, Jean’s field still resembles any other sleepy piece of land on the edge of town. There is a leaning gate, a rusty barrel and clumps of grass that stopped trying to look tidy years ago. Apart from the low drone of bees and the beekeeper quietly inspecting the frames on Sunday mornings, little seems to happen there.
In official records, however, that same strip of land has abruptly been labelled an “agricultural use”. It is the sort of classification that triggers a piece of office software and creates an extra entry on the tax register.
No one from the authorities has actually visited the site. No official has touched the trees’ split bark or watched the beekeeper’s ageing van splutter up the incline. Instead, a box has been ticked on a form: hive installation = agricultural activity. Once that classification is applied, the system seldom reverses it.
Cases like Jean’s are becoming increasingly common in small communities, where long-standing rural habits meet new tax instincts. A retired couple lends a neighbour a narrow field strip for vegetable beds and is suddenly reclassified. Someone permits a young farmer to graze three sheep, simply to keep grass down, then discovers that the land is considered “in productive use”.
In south-western France, a widow allowed a novice beekeeper to use one corner of her meadow. During the first year, no honey was sold: it was a period of learning and keeping bees. In the second year, a few jars were produced, most of them given away. By the third year, she received a letter referring to “non-declared agricultural activity” on her property, together with a tax adjustment worth several hundred euros.
By urban standards, that may not sound dramatic. But for someone calculating every euro of their pension before month-end, such an envelope can feel like a blow to the chest. The beekeeper was deeply embarrassed, the town clerk uncomfortable, and the regulations left little room for flexibility.
At the heart of this problem is a straightforward mechanism: once land is used for any form of production, however small-scale, it can fall into a category that puts tax authorities on alert. The original purpose was to stop people exploiting the system by disguising profitable work as a hobby.
Real life does not fit neatly into administrative categories, though. A retired owner lending land without charge is not operating a business. A beginner beekeeper with ten hives and no profit is not an agricultural corporation collecting subsidies. Even so, both may be caught between legal definitions designed for a very different world.
The simple reality is that small rural favours, once unnoticed and unrecorded, are now being checked, categorised and sometimes charged for. It leaves a bitter aftertaste that has nothing to do with honey.
Lending land to a beekeeper without getting stung
For anyone considering offering a corner of land to a beekeeper or young farmer, the most useful safeguard is unexciting but vital: a basic written agreement. It need not be elaborate or formally notarised. A single document should state plainly that the landowner has no role in any economic activity, that use of the land is temporary and free of charge, and that responsibility rests with the person placing the hives there.
One page and three signatures can be enough: the landowner, the beekeeper and, where possible, a local association or rural advice service acting as witness. Include beginning and end dates, the number of hives, and a clear statement that there is no rent, payment in kind or undisclosed arrangement. If the tax office starts asking questions, this can make a significant difference.
It also prompts a discussion that is often overlooked: who declares what, who arranges insurance and what happens if neighbours raise objections. These may be dry matters to put on paper, but they help protect the generous human act that began the arrangement.
Many pensioners like Jean agree from the heart and never reach for a calculator. They notice a young beekeeper finding their feet, remember when neighbours helped one another without forms, and simply open the gate. Months later, a letter arrives, leaving them feeling betrayed-not by the beekeeper, but by a system that appears to penalise kindness.
A common error is accepting “payment” in honey or vegetables without considering the consequences. Once an exchange happens regularly, even if it is symbolic, the authorities may view it as rent. Another overlooked issue is planning classification: land assigned a particular status in the local plan can bring specific obligations once it is “used”.
We have all faced that point where a straightforward favour unexpectedly becomes a stack of forms and phone calls, leaving us to question why we agreed in the first place. A brief visit to the local tax office or a farmers’ association before lending the land can prevent unpleasant surprises later.
“I didn’t want a cent,” Jean repeats, shaking his head at the thought of that bill. “He gave me two jars of honey the first year, I almost didn’t take them. And now they treat me like I’m hiding some secret farm business.”
A few simple precautions can prevent that situation from escalating and stop solidarity turning bitter:
- Establish the activity’s status (hobby, test phase, micro-business, registered farm).
- Ask the town hall whether hives or crops alter the land’s tax classification.
- Make any “thank you” gifts occasional and clearly symbolic, rather than a set return.
- Ensure the beekeeper or farmer, rather than the owner, declares the activity.
- Record that the landowner has no share in profits, decisions or sales responsibilities.
Solidarity, freeloading or something in between?
After the letters and tax-office appointments are over, one uncomfortable question remains: who is actually freeloading? Is it the pensioner who opens a gate for free, only to receive an unforeseen bill? Is it the beekeeper using another person’s land while avoiding its hidden costs? Or is it a system that silently converts every act of support into a taxable opportunity?
The truth is less clear-cut than the outrage suggests. Some landowners have indeed used supposedly friendly arrangements to operate partly concealed activities while avoiding tax. Some beekeepers and micro-farmers genuinely fail to appreciate the effect their projects can have on those hosting them. And some administrations apply blunt rules to nuanced lives because nuance takes time, and time costs money.
In truth, almost nobody reads the full tax code before agreeing to let a couple of hives sit in a field corner. It is in that gap between how people live and how the law assumes they live that these small tragedies take root.
This story resonates because it touches something fundamental about rural life and neighbourly trust: the quiet economy of favours, land lent “for now”, hives hidden behind barns, and sheep grazing more through friendship than for profit. If every one of those relationships begins to carry an undisclosed charge, something fragile may break.
Perhaps the real task is not to choose between solidarity and freeloading, but to restore the ability to help one another without being financially penalised for doing so. It also means demanding rules capable of distinguishing between a pensioner with four acres and a company exploiting loopholes hectare by hectare.
| Key point | Detail | Value for the reader |
|---|---|---|
| Put arrangements in writing | A simple agreement confirming free, temporary use and no shared profits | Lowers the risk of being reclassified as operating an activity |
| Check local rules early | Ask the town hall and tax office how hives or crops affect land status | Prevents unexpected tax demands for pensioners and small owners |
| Keep favours as favours | Give symbolic gifts rather than regular “payment” in honey or produce | Helps maintain solidarity without activating hidden financial consequences |
FAQ:
- Can I be taxed just for lending my land to a beekeeper? Yes. If the activity is regarded as regular production on your property, the land may be reclassified in a way that changes your tax bill, even where you earn nothing.
- Does a written agreement really change anything? It cannot override the law, but it makes clear that you are not involved in the economic activity, which can strongly affect how the tax office interprets your circumstances.
- Is getting jars of honey considered “payment”? Occasional and irregular gifts are not usually an issue, but a fixed and predictable return can be treated as rent or income in certain circumstances.
- Who should declare the hives or farm activity? The beekeeper or farmer-not the landowner-should register the activity and deal with any professional or tax obligations.
- What can I do if I already received an unexpected tax bill? Request a meeting with the tax office, take any written evidence that the land was lent free of charge and, if necessary, seek help from a rural association or legal-aid service to challenge or negotiate the bill.
Comments
No comments yet. Be the first to comment!
Leave a Comment