
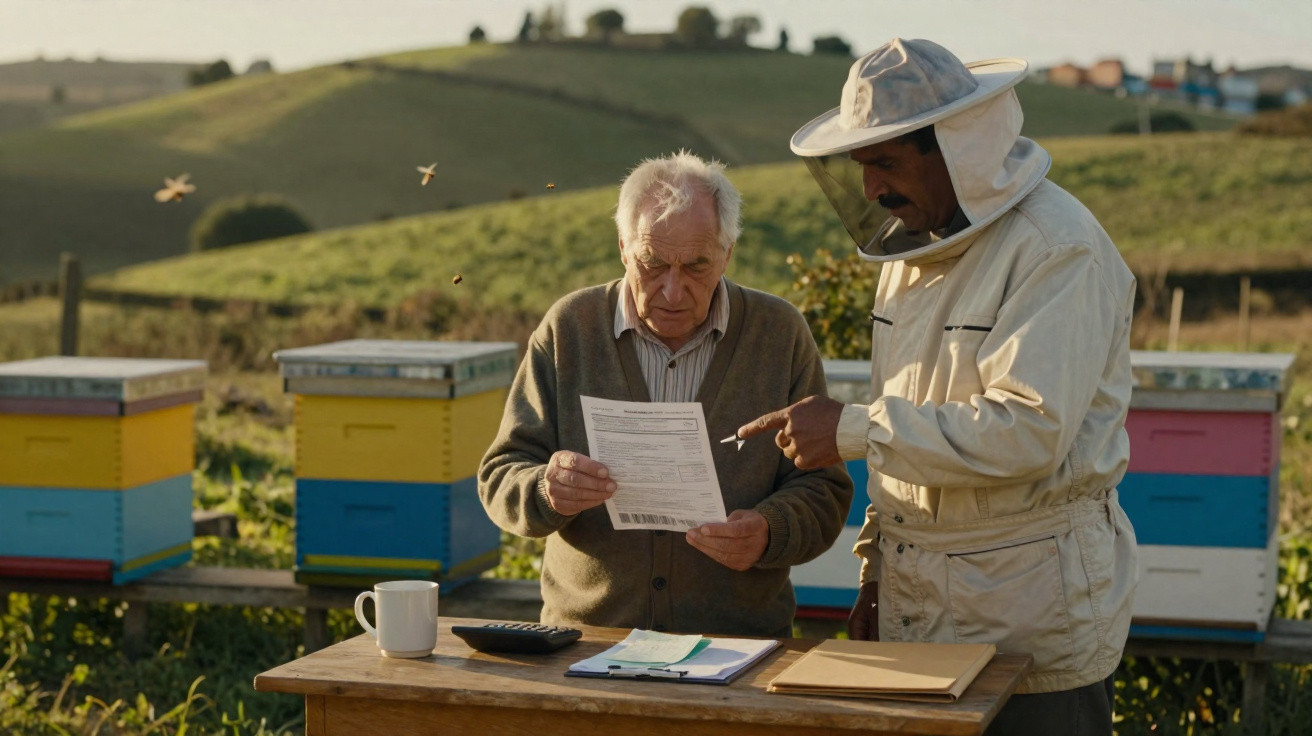
On a misty spring morning, with the grass still cold from the night, Jean opened his hands towards the little meadow behind his home and said, “Do what you like with it, I’m not using it anyway.”
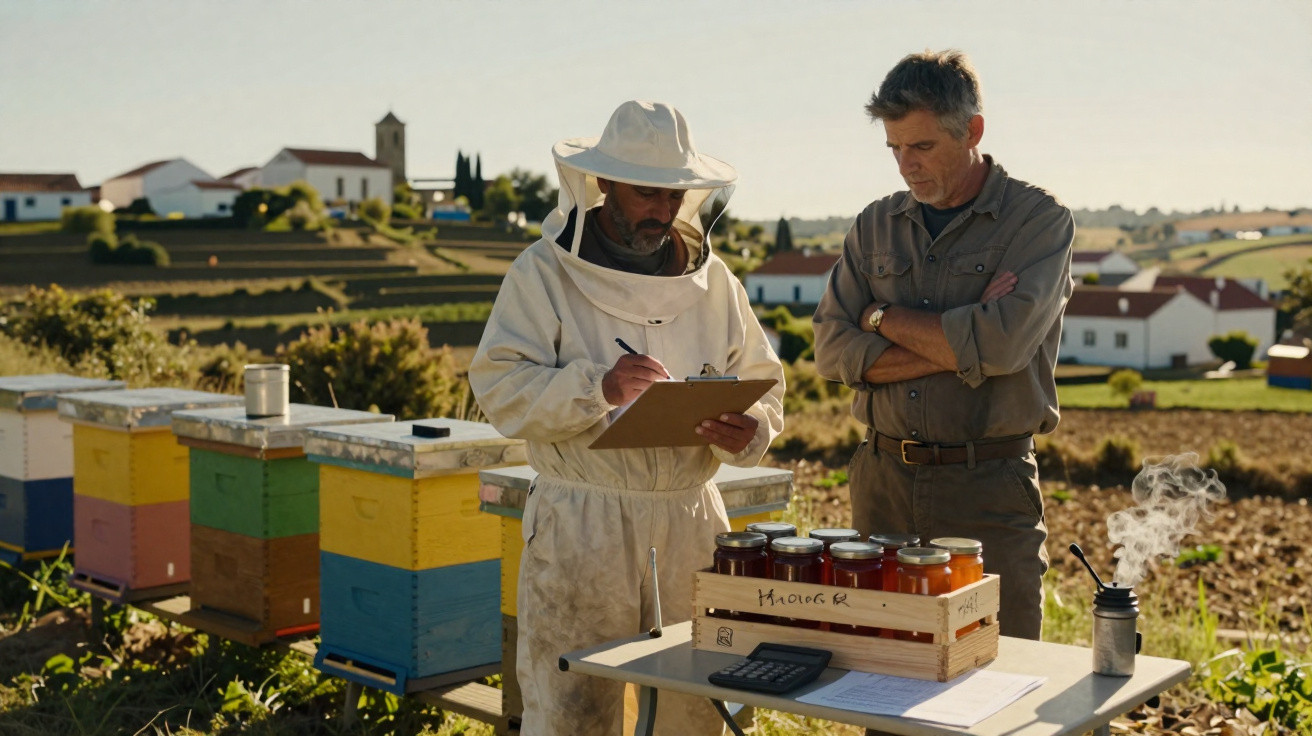
The young beekeeper smiled with relief. A place to keep hives was the one thing he lacked. A week later, white hive boxes arrived and began humming gently at the field’s edge, scarcely interrupting the peaceful routine of the retired couple living nearby.
The months went by, the bees worked quietly and honey was produced.
Then a letter came through the door.
It was not a thank-you note, but a tax demand.
The French tax office had classified Jean as an “agricultural operator” and charged him agricultural tax for land he did not farm, bees that did not belong to him and honey he would never sell.
Nobody was making much money.
Even so, somebody was expected to pay.
But who?
When a kind gesture is mistaken for a business
The situation seems almost ridiculous.
A retired man in his seventies, with a cardigan draped over his shoulders, sits at the kitchen table using a magnifying glass to work out why accommodating a handful of hives has transformed his peaceful meadow into a “commercially used agricultural plot”.
On paper, the formula appears straightforward: land plus productive activity equals tax.
In reality, it is far less clear-cut. Jean allowed a small beekeeper, trying to make a modest living well away from industrial farming, to use the land at no cost. There was no rent, no agreement and no concealed arrangement. It was simply two people doing their bit to support bees in a world where their numbers are declining.
However, a tax notice does not take goodwill into account.
It sees only a plot reference and an activity classification.
As with many such stories, it began with a sincere request: “Could I put a few hives on your land? The bees need flowers, and I can’t afford to rent.”
Moved by the request, the retiree said yes. They shook hands across the fence. There was no solicitor, accountant or even a sheet of paper involved.
For several months, the only changes were a low hum from the edge of the plot and a few jars of honey given as Christmas presents. The beekeeper was scarcely meeting his costs while dealing with varroa mites, drought and changing honey prices. Jean proudly mentioned “his” bees to neighbours, although they were never actually his.
Then an aerial or land-registry inspection identified “productive agricultural use” on a plot that had previously been unused. The system registered an activity.
Once again, real life was more complicated than the record suggested.
From the administration’s perspective, this unpleasant surprise follows a simple rationale. Land contributing to agricultural production, even indirectly, can fall into a taxable category. This may lead to local land taxes, sometimes social contributions, and the technical labels that go with them: “agricultural use”, “operator” and “person liable for payment”.
Where no written lease exists, the authorities may initially focus on the landowner. He is easy to identify because his name appears in the land register. The beekeeper, often operating as a micro-business or small self-employed business, may not be clearly connected to that particular plot in official databases.
The law uses technical terminology.
Daily life runs on handshakes and jars of honey.
Misunderstandings can quickly develop in the gap between them.
How to lend land to a beekeeper without creating a tax trap
There is a quiet, practical way to prevent Jean’s predicament: put the generous arrangement on record, even briefly.
That does not require turning every favour between neighbours into a 12-page contract. Yet a short written agreement can make a substantial difference in the eyes of the tax office.
A straightforward document can confirm that the beekeeper is the sole operator, that he uses the land, that the owner takes no part in production and that the owner receives no income. It can be one or two pages, dated and signed, with a note that the beekeeper declares the activity under his own agricultural or micro-business status.
For just a couple of hives, that may feel unnecessarily administrative.
Nevertheless, this small step could prevent a serious problem later.
The main danger is not dishonesty but trust without evidence.
People lend land much as they lend a ladder: “Here, take it, bring it back whenever.” But land does not simply “come back”. It is mapped, assessed and categorised. It remains recorded in databases that quietly share information in the background.
One frequent assumption is, “No money, no problem.” Yet tax rules often give more weight to how land is used than to whether a profit is made. A rent-free loan may therefore still be treated as agricultural exploitation, particularly where visible structures such as hives, sheds or greenhouses are present.
We have all had that moment of assuming that, if something is done “between honest people”, nothing can go wrong.
Reality does not always follow that logic.
It is also sensible to speak to someone before the first hive is delivered.
A local agricultural service, rural notary or, in some cases, the town hall may be able to explain who counts as the “operator” and who should be named on agricultural declarations. One brief discussion can prevent months of correspondence and appeals.
The beekeeper in Jean’s village summed it up in a single sentence: “We just wanted to help the bees, and now we’re reading tax codes at midnight.”
- Put it in writing: Prepare a short loan agreement confirming that the beekeeper is the agricultural operator and is responsible for tax and declarations.
- Identify the activity: Ask the beekeeper which status applies to his work - farmer, micro-business or association - and, where possible, connect the plot to that activity.
- Ask the right questions early: Before anything is installed, contact the tax office or a rural adviser and explain the arrangement in clear language.
- Keep evidence of the reality: Photographs of the hives, copies of the beekeeper’s registration and the agreement may be useful if a dispute arises later.
- Do not wait for the tax bill before getting organised. Once the notice has arrived, correcting the position can become more limited and more stressful.
When “no one is making money” can still have a cost
Cases such as Jean’s reveal a quiet rural tension: landowners who are not farmers, tiny activities that are barely viable, and a tax system designed for organisations larger than a few hives beneath a hedge.
On one side, the state seeks to monitor productive land and the way it is used. On the other, country life often relies on informal arrangements, favours and shared spaces.
This grey area is expanding. There are small market gardens on borrowed plots, shared orchards, volunteer pumpkin beds and educational farms operating behind old barns. Such projects often sit somewhere between a pastime and work, generosity and enterprise.
Let us be honest: virtually nobody reads agricultural tax legislation before placing three beehives in a meadow.
Yet this is how tax disputes emerge: gradually, one letter after another.
| Key point | Detail | Value for the reader |
|---|---|---|
| Clarify who the “operator” is | Use a brief written agreement naming the beekeeper as the person managing the activity on the land. | Lowers the risk of the retiree or landowner becoming the unexpected taxpayer. |
| Plan ahead before installing hives | Check with tax or agricultural services how the plot will be classified once it is in use. | Avoids unexpected tax demands months or years later. |
| Retain simple, practical evidence | Keep copies of agreements, registration details and a few dated photographs. | Makes it easier to challenge or correct a tax notice if one is received. |
FAQ
- Question 1: Can lending land for free to a beekeeper really trigger agricultural tax?
- Answer 1: Yes. The tax office considers how the land is used, rather than only whether money changes hands. Productive agricultural use can place a plot in a taxable category even if the owner receives no income.
- Question 2: Who would normally be expected to pay agricultural tax in this situation?
- Answer 2: In principle, the agricultural operator carries the tax liability. However, if the operator is not clearly identified in the paperwork, the administration may approach the landowner instead. This is why written agreements and clear declarations are so important.
- Question 3: Is a formal lease required for a few hives?
- Answer 3: No. A full agricultural lease is not always needed. A simple signed loan agreement confirming that the beekeeper uses the land for his professional or declared activity can already set out responsibilities and reassure both parties.
- Question 4: What can a retiree do after receiving an unexpected tax demand?
- Answer 4: They can contact the tax office, explain the circumstances and provide any evidence showing that the beekeeper is the true operator. It may sometimes be possible to correct the position, but this often takes patience, written appeals and, occasionally, advice from a notary or legal-aid service.
- Question 5: Is it still worthwhile lending land under these circumstances?
- Answer 5: Yes. Many small beekeeping and ecological projects rely on this type of generosity. The important thing is not to stop helping, but to adopt a simple habit: talk, write and clarify before agreeing. In that way, the bees can continue working and people can sleep more peacefully.
Comments
No comments yet. Be the first to comment!
Leave a Comment