
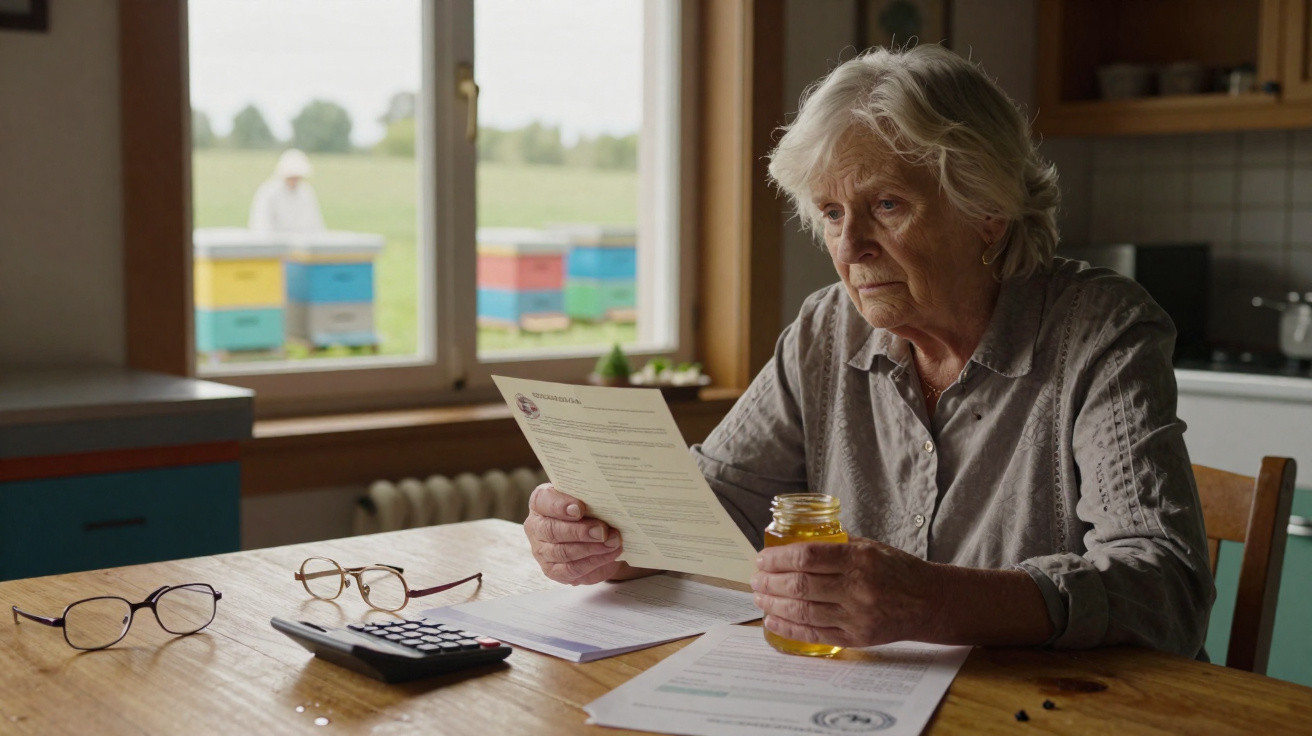
On a mild spring afternoon, beneath the sort of pale sunshine that makes every colour look brighter, John Walker stood beside his little field and watched bees drift upwards like smoke.
They were not John’s bees. The hives belonged to a young beekeeper from the area, who had called at his door two years before, anxiously turning his cap in his hands as he asked whether he might “borrow a bit of land”.
John agreed immediately. There was no contract and no discussion of payment: only a handshake and the understated pleasure of “doing something for nature”.
The hives remain there today, buzzing steadily. Yet John no longer smiles. A weighty envelope from the tax office has arrived, bearing a sum that has made his retirement suddenly seem precarious.
The bees are flourishing. John’s finances are not.
When a good deed becomes a tax nightmare
At first, it sounds like the perfect village story: a retired man with a modest pension and an unused small field, helping a young beekeeper trying to establish himself in a demanding profession.
The mayor approved of it. At the pub, neighbours congratulated John for “supporting biodiversity” and “helping the bees”. Nobody mentioned tax bands, agricultural classifications or the fine-print complexities of land-use declarations.
Then a brown envelope appeared on his kitchen table.
The land had been reclassified. Agricultural use. A new tax basis.
Because of the hives and John’s act of goodwill, the authorities had begun to regard him as a very small, unintended farmer. “I’m not making any money from this at all,” he repeated as he looked at the figures.
Similar accounts are heard in rural cafés and village halls throughout the country. There is the woman who permits a neighbour to graze three sheep on her pasture “so the grass doesn’t go wild”.
There is the couple who let a market gardener erect a greenhouse on their spare plot, delighted to see fresh vegetables sold at the Saturday market. There is also the widower who signed a straightforward letter allowing a young breeder to keep equipment on his land.
Every one of them believed they were simply lending a hand. Each later found, sometimes after several years, that local taxation rules and agricultural classifications had changed quietly around them. Land that had always been merely “just a field” or “the back lot” was suddenly recorded on a computer as a taxable productive surface.
One minor favour was enough to make the financial stability of their retirement feel uncertain.
For the tax office, land is never simply neutral. On its system, a plot is used or unused, residential or agricultural, and taxable in one way or another.
Once regular hives were kept in John’s field, it was treated as part of an agricultural activity, despite the fact that John had not sold a single drop of honey. The beekeeper had declared both his hives and his business. His paperwork identified John’s plot as an apiary site. The systems matched the information, and land formerly taxed at a lower rate as “non-productive” was reclassified as an “agricultural asset”.
Nobody called John beforehand. No one came to his door to set out what had changed. The revised assessment arrived fully calculated, including penalties for the previous two years. For someone who has to account for every pound of his pension, it felt not like an adjustment but like a penalty for kindness.
How to safeguard your generosity before it costs you
There is an understated rule for surviving land and tax issues: do not allow the reality on the ground to change without corresponding paperwork. As soon as another person uses your field, shed, barn or even a strip at the end of your garden, your legal position changes too.
The most prudent first move is decidedly unromantic. Before agreeing, telephone a local adviser: a tax specialist, rural solicitor, farmers’ union or citizens’ advice bureau. Describe plainly what the other person intends to do on your land.
Ask a single question:
“Will this change my tax situation or my status in any way?”
That 15-minute call could spare you years of remorse and an unforeseen bill that consumes your heating budget or your grandchildren’s Christmas.
Many retired owners feel uncomfortable raising money when someone approaches them with an optimistic, environmentally friendly proposal. They do not wish to appear mean or distrustful, so they avoid the awkward conversation and go straight to the handshake.
That is how problems begin. There is no written agreement, no defined responsibility for additional taxes and no reference to insurance should anything go wrong. Instead, there is only a vague “don’t worry, it’ll be fine”.
In truth, nobody reads agricultural tax legislation for enjoyment. People therefore follow their instincts, and those instincts normally say “help the young lad with the bees, it’s a nice thing to do”. When the tax demand arrives, they feel deceived, even where nobody intended to cause harm. The embarrassment then changes direction: they are no longer ashamed of being wary, but of not being wary enough.
John put it in one weary, matter-of-fact sentence: “I thought I was giving him a chance, and now I’m the one who can’t sleep at night.”
His voice broke not because he was angry with the beekeeper, but because he was astonished that good intentions could become a line item on a spreadsheet.
Get it in writing
A basic written agreement, including one written by hand and signed by both parties, can state that the beekeeper or farmer takes responsibility for any added tax consequences and completes the formalities.Ask about declarations
Find out whether your land will appear in an official farm or business declaration. If it will, ask how this could be shown within the tax system.Make the “no income” position clear
Record explicitly in the agreement that you receive neither income nor benefit. This may provide helpful evidence if you need to dispute a reclassification and demonstrate that you are not an agricultural operator.Maintain your own records
Keep copies of letters and emails, along with photographs showing how the land was used before and afterwards. It may be tedious, but it gives you solid evidence when the administration sees only a reference number.Speak to neighbours
Someone on your road or in your village has often faced a similar problem already. Their experience may reveal both pitfalls and local answers that you would not have considered alone.
When taxes strain the communities they are meant to regulate
Cases such as John’s do more than reduce a pension. They damage the delicate trust on which small communities depend.
The beekeeper now passes John’s gate a little more quickly. He maintains that he did not know about the tax implications and says that he is himself barely coping with rising costs for equipment, fuel and veterinary checks. He is not wrong.
Neighbours murmur that the tax office “must have better things to do”. Some decide quietly that they will never again lend out a field, a barn or even a corner of land. Something breaks, not just in one man’s finances, but in the shared belief that helping each other is always a good idea.
| Key point | Detail | Value for the reader |
|---|---|---|
| Check the tax impact first | Any “free” use of land for bees, grazing or crops may cause a change in the way a property is classified and taxed. | Helps shield your pension or fixed income from unexpected reclassification and backdated bills. |
| Use simple written agreements | Even a one-page document setting out responsibilities, taxes and declarations can make a substantial difference during a dispute or audit. | Provides evidence and a basis for challenging a decision or renegotiating the arrangement. |
| Talk locally, act early | Consulting local advisers, farmer groups or knowledgeable neighbours before agreeing can expose risks that are not apparent in paperwork. | Lets you retain the positive side of community solidarity while avoiding unpleasant surprises. |
FAQ:
- Question 1 Can I really be taxed more just for letting someone put beehives on my land, even if I earn nothing?
- Answer 1 Yes, the tax office often considers the use of the land rather than whether you personally make a profit. Where hives, crops or animals are placed on your property as part of another person’s business, the land may be regarded as agricultural, potentially altering your property tax or local levies.
- Question 2 How can I avoid this kind of unpleasant surprise as a small landowner?
- Answer 2 Before accepting any proposal, consult a local tax adviser or legal professional and explain the intended use in specific terms. Seek written clarification wherever possible and retain a copy. A short written agreement with the person using your land is another strong form of protection.
- Question 3 Is a verbal agreement enough between me and the beekeeper or farmer?
- Answer 3 Verbal agreements can legally exist, but they are exceptionally difficult to prove or clarify if a problem arises. Even a simple signed note on one page is a major improvement and may prevent later misunderstandings and financial loss.
- Question 4 What if the tax bill has already arrived - can I contest it?
- Answer 4 You can generally submit an objection within a particular deadline stated on the bill. Collect all available evidence: the absence of income, the nature of the agreement and your financial circumstances. Contact a tax adviser or citizens’ advice service promptly to organise your case and avoid missing the deadline.
- Question 5 Does this mean I should never help young farmers or beekeepers again?
- Answer 5 Not necessarily. It means offering help with your eyes open rather than closed. Clear agreements and a basic grasp of the tax implications can still allow you to support local projects, biodiversity and young entrepreneurs - without endangering your retirement.
Comments
No comments yet. Be the first to comment!
Leave a Comment