
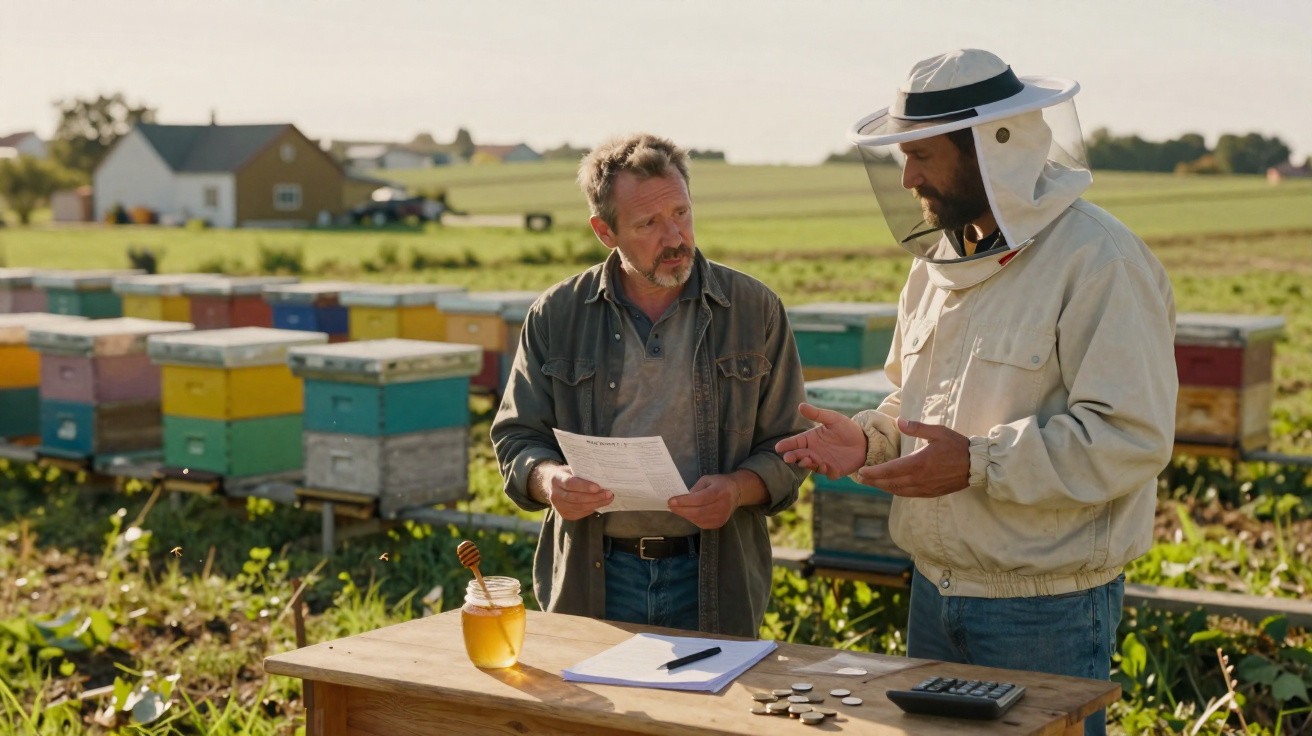
The tale starts with a phone call that seems almost ridiculous. A homeowner in a quiet village, pleased with his modest plot and his new “eco-friendly” initiative, had allowed a local beekeeper to keep hives in one corner of his land a year earlier. There was no rent involved: only the prospect of free jars of honey and the satisfying feeling of helping the planet. Then his tax demand arrived: agricultural tax on property he regarded as “non-agricultural”. Every relevant line carried his name. Not the beekeeper’s. Not the person selling the honey. His.
The dispute that came next was far from sweet.
On one side was a homeowner blindsided by a tax charge he had never anticipated. On the other stood a beekeeper who maintained that the arrangement was “win-win”.
Clearly, somebody was coming out ahead.
When bees land on your lawn, the tax office pays attention
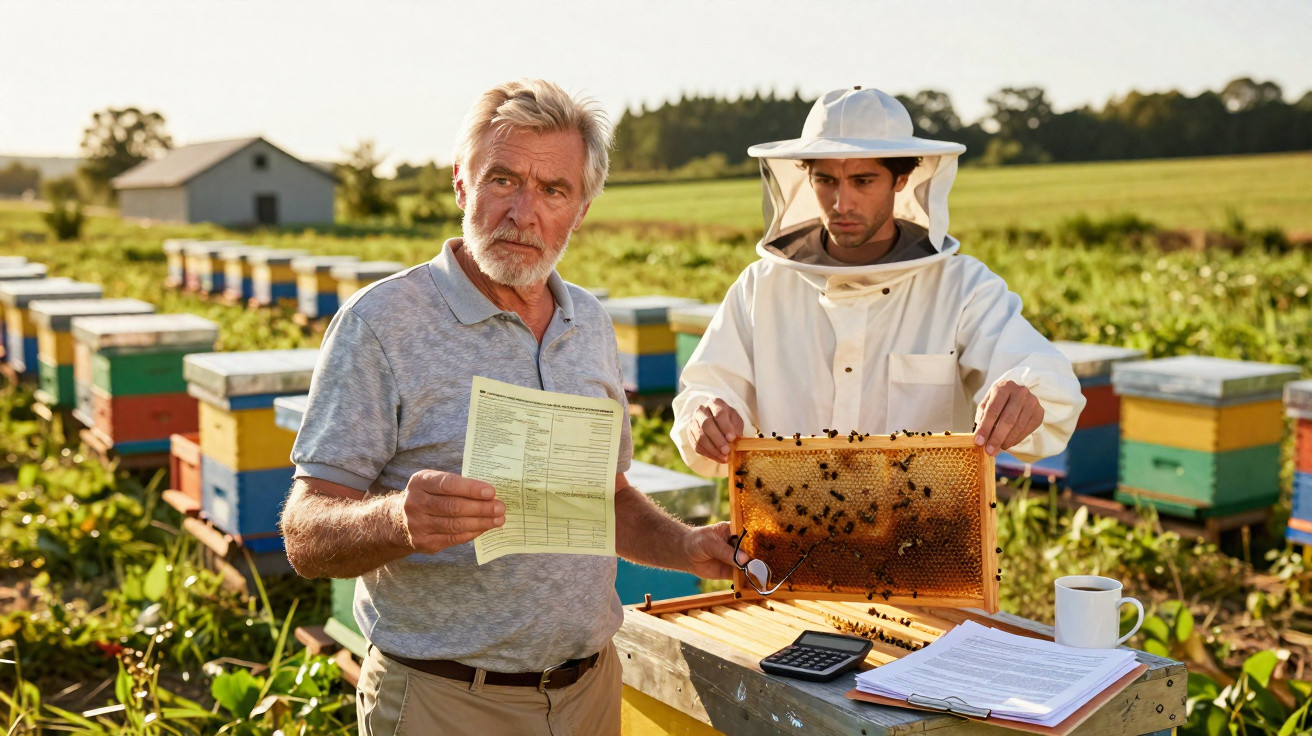
At first glance, the setup appeared straightforward: a narrow section of land, an informal handshake, and several hives tucked beside a hedge and barely visible from the road. The beekeeper visits several times each month, inspects the frames, puts boxes of honey into his van and leaves with a friendly wave. To anyone watching from outside, it looks like an innocent rural arrangement.
For the tax authorities, however, those white hives are more than simple boxes.
They can indicate agricultural use.
In many areas, once land is classified as being used for agriculture, its owner may be treated as an “agricultural taxpayer” - even if that owner has never put on a beekeeper’s suit.
Consider Marc, 52, who owns a home on the outskirts of a small town. He let a beekeeper friend use a small plot behind his hedges for a token payment: one euro annually and a few jars of honey at Christmas. There was no formal contract, merely a friendly written note and several WhatsApp photographs taken when the hives were put in place.
A year later, his property tax rose. The bill contained a charge he had never previously seen: tax calculated on the agricultural use of land. Marc initially assumed an administrative mistake had been made. The tax office took a different view.
Officials told him that, because the land was still registered in his name and the activity was agricultural, he remained liable. The discussion became bitter within moments when he rang the beekeeper.
The unfairness is not only about the amount due. It is also the sense that the roles have been quietly reversed. The beekeeper owns the hives, collects the honey and sells jars at markets, sometimes supported by an appealing “local partnership” story.
Meanwhile, the homeowner supplies the indispensable asset: the land, access to it and lasting stability.
Yet under many tax systems, the person farming the land or keeping animals there is not necessarily the one who pays property-related agricultural tax. Legislation often follows the title deed rather than the trail of honey. That disconnect is ideal ground for conflict, assumptions left unstated and, in certain cases, genuine financial losses for someone who merely “wanted to help the bees”.
Turning a “friendly arrangement” into a real, fair agreement
Avoiding this sort of problem begins well before the first hive arrives. The sensible approach is to regard that small patch of land for what it becomes once bees are installed: a site of economic activity. A 20-page contract is unnecessary, but a clear, binding document is not.
Set out who is responsible for what, who pays which costs and who bears the consequences if the tax office reclassifies the land for agricultural use. A single page, dated and signed by both parties, can be enough.
The agreement should expressly cover tax liabilities and the possibility of reclassification. That may seem overly formal for “a few boxes of bees”, but it could be the clause that protects your finances later.
Many homeowners in this position accuse themselves of being naive. A kinder interpretation is that they behaved like neighbours rather than solicitors. Few people would expect six hives at the bottom of a garden to result in an unforeseen tax demand.
The central danger is the familiar “don’t worry, it’s just symbolic” mindset. Symbolic rent, symbolic use and a symbolic agreement. The beekeeper avoids land costs, the homeowner feels charitable, and neither party works out who is absorbing each risk.
Realistically, no one studies tax legislation every time they lend a friend a corner of their land.
But the tax office is unconcerned whether payment is made in euros or honey jars. The land is being used, the owner is recorded and the bill goes to the name on the deed. That is the point where goodwill stops and paperwork takes over.
At the centre of the disagreement between homeowner and beekeeper is often an uncertain understanding of who truly benefits from the hives. The immediate response is usually, “the beekeeper, of course, he sells the honey.” Yet the situation is more complicated than that.
“From my side, I bring the hives, the equipment, the time, the risk of disease, and the work every weekend,” one semi‑professional beekeeper told me. “The landowner gives me space, yes, but without me those hives don’t exist. We co‑create the value.”
In reality, three separate sources of gain and cost tend to emerge quietly:
- The beekeeper’s direct earnings from honey and related products.
- The homeowner’s indirect gain, including a “greener” image, perhaps greater appeal for the property and sometimes complimentary honey.
- The concealed cost of tax, insurance and possible reclassification of land use, which is nearly always carried by the owner.
Where nobody clearly identifies this three-way balance at the outset, resentment later occupies the silence.
Who really wins when bees move in?
This type of neighbourhood dispute raises a broader and less comfortable issue: how should we divide the costs of ecological gestures that also function as small businesses? Offering land to a beekeeper can feel like an environmental contribution, much like planting a tree or putting up a bird feeder. Once the tax bill arrives, though, that gesture can begin to resemble a private subsidy for another person’s enterprise.
Some homeowners accept the expense and retain the hives, reassuring themselves that it is “for nature”. Others remove the hives, end the relationship and decide never again to combine friendship, land and money. Both responses are understandable.
A more grown-up perspective lies somewhere between those two reactions.
Most of us know the moment when a pleasant, uncomplicated idea becomes burdensome as soon as the first official letter appears. The appeal vanishes. The relationship deteriorates, not because either party has acted maliciously, but because neither anticipated that the State would be sitting invisibly at the same table.
The simple reality is that bees are not merely poetic. They are an agricultural resource. As soon as that classification applies, administration is not far behind.
Perhaps, then, the key question is not “who profits from the hives?” but “who agrees to be formally connected with this activity?”. It is the person whose name is shown on the deeds, the forms and the database - the person receiving the brown envelopes through the letterbox.
Stories of this kind travel quickly through villages and suburbs. One unhappy experience can make three other neighbours hesitate before agreeing to help a friendly beekeeper who calls at their door. Some will now insist on written terms, shared tax payments or a modest rent that genuinely reflects the risk. Others may argue that associations or councils should host hives on public land, spreading the burden rather than leaving it with one individual.
There is no effortless formula and no single contractual sentence that can prevent every disagreement. Still, each case prompts a distinctly modern discussion about how land is valued, how “good deeds” are priced and how rapidly a jar of honey can become a sign of damaged trust.
The sound of buzzing in the garden then takes on a very different meaning.
| Key point | Detail | Value for the reader |
|---|---|---|
| Clarify tax risk early | Agricultural activity on your land may result in reclassification and additional tax in your name | Consider possible costs before agreeing to host hives or comparable activities |
| Put agreements in writing | Straightforward one-page contracts should cover tax, responsibilities and duration | Minimise disputes and retain a basis for negotiation if a conflict arises |
| Balance profit and burden | Agree how honey sales, free products, rent and tax will be divided | Create fairer arrangements and reduce surprises for both homeowner and beekeeper |
FAQ:
Who pays agricultural tax when hives are on private land?
In many systems, the tax is linked to the landowner rather than the beekeeper. If the activity causes the tax office to classify some of your land as agricultural, the demand will generally be sent to you, unless a particular legal arrangement or long-term lease clearly transfers that liability.Can a simple written agreement protect a homeowner?
A written agreement cannot automatically alter tax law, but it can make responsibilities clear. It may state that the beekeeper will reimburse the owner for additional tax or adjust the rent to reflect it. It can also provide helpful evidence if the matter develops into a dispute.Is renting land to a beekeeper considered a business activity?
It may be. Even token rent or honey provided as payment can be treated as a form of income. The precise consequences depend on your country’s tax rules, your total income and whether the land use is considered agricultural or occasional.What should a basic land-for-hives agreement include?
As a minimum, include both parties’ identities, a description of the plot, the term of the agreement, the permitted number of hives, access arrangements, liability and insurance, treatment of possible tax rises, and the process for either party to end the arrangement.What if I already host hives and have received a higher tax bill?
Begin by contacting the tax office to establish why the reclassification was made and which criteria were applied. Then speak openly with the beekeeper about sharing the costs or changing the agreement. If no resolution is possible, professional advice may be needed to challenge the decision or alter the arrangement.
Comments
No comments yet. Be the first to comment!
Leave a Comment