
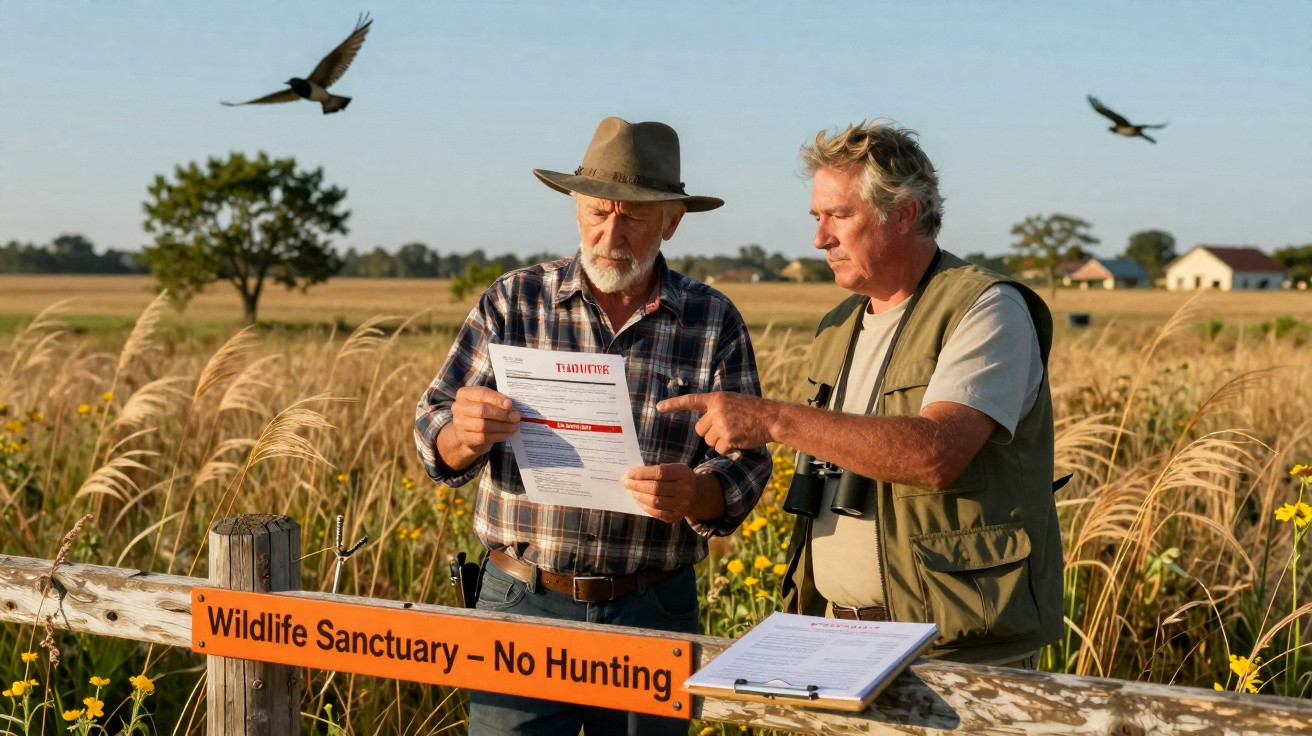
A thick envelope marked “habitat-management assessment” then dropped through his letterbox, splitting the silence like a rifle shot. When the bill reached the internet, outrage erupted across the country once more.
The barn carried the scent of rain and alfalfa on the morning I first met him. Walt, 72, rested against a fence post beneath a cap faded to the shade of old denim, as he watched a young rescuer lead a limping fawn into a shaded enclosure. On the tailgate, a red-tailed hawk sat in a crate, blinking with fierce exhaustion, while sparrows filled the hedgerow with sound. “No good deed should start with paperwork, yet here we were.” Then the envelope arrived.
When a sanctuary becomes a tax charge
Walt had allowed Mia, who operates a small rescue from her garage, to use six acres scattered with birch trees and crossed by a slow-moving creek. She put up temporary pens, placed water bowls around the site and displayed a sign bearing a donated emergency telephone number. The bill landed like a second winter. It was neither a cruelty penalty nor a charge for the fencing. Instead, it was a “habitat-management tax” resulting from a land-classification change, alongside a multi-year “rollback” that reclaimed the tax relief he had received as a farmer.
In that county, the assessor saw “wildlife rehabilitation” and redesignated part of the plot as non-agricultural. The reasoning may have looked neat on paper, but it was brutal in practice. In a single stroke, a man who had previously paid a few hundred dollars for pastureland faced five years of back taxes and a new yearly charge running into four figures. The previous week, Mia had collected $800 for formula and veterinary costs; before the first frost, the county was demanding more than $18,000.
The phrase “habitat-management tax” differs between states, but the underlying situation is much the same. Favourable valuations are available for agricultural land and formal wildlife-management plans, provided specific rules, measures and reporting requirements are met. Once land falls outside those categories, it is assessed as ordinary land or potentially even as a commercial operation. This is when rollback taxes hurt: change the use and the relief is removed retrospectively. It can feel like kindness is being punished. On a spreadsheet, however, it is merely a recalculation.
How to support wildlife without causing a bill
There is a way to help that does not end with a heart-stopping surprise in the letterbox. Start with a written use agreement stating that the land remains agricultural and that the rescuer is a temporary licensee rather than a tenant. Then divide the acreage. Continue haymaking or grazing across most of the land to retain the tax-protecting classification, while setting aside a small “recovery yard” for cages and quiet. If your state provides the option, submit a straightforward wildlife-management plan, even a basic version containing counts and photographs. Speak to the assessor before anything begins, rather than afterwards.
The usual errors are painfully understandable. People install a prominent sign, share viral videos and suddenly appear to be running a new business. They convert most of a plot without recording the agricultural activity still taking place there. Let’s be honest: nobody reads tax codes for enjoyment. Retain receipts for bales, document pasture rotation and record the release dates of rehabilitated animals. A paper trail may not be romantic, but it is essential for survival.
This is not legal advice; it is simply advice shaped by people who have encountered the buzz saw themselves. The specifics differ from county to county, but the pattern returns like a summer thunderstorm.
“I thought I was saving animals,” Mia told me, her hand on the hawk crate. “I didn’t realize I also had to save the land from the paperwork.”
- Obtain a one-page land-use letter signed by both parties.
- Keep agricultural activity in place across the majority of the acreage.
- Submit a wildlife-management plan in advance if your state permits it.
- Choose neutral signage and avoid wording that suggests commercial use.
- Maintain a shared folder containing dated photographs, logs and receipts.
Why outrage keeps returning, and what it might change
The account spread online because it sits in the space between what we claim to value and how our systems actually operate. People see pastureland with songbirds and a temporary fawn pen as the American promise made visible. A treasurer’s office sees classifications. Everyone has experienced a moment when a good deed unexpectedly begins to resemble a mistake. The internet loathes that sensation, so it raises its voice.
Some describe this as bureaucratic cruelty. Others say rules are necessary to prevent loopholes from turning farms into tax shelters. Both views can be valid, yet it remains difficult to accept the image of a retired farmer sorting through forms while a hawk blinks nearby. Policy need not choose between care and cynicism. It could establish a narrow route for small rescues working with landowners: pre-approved by assessors and protected against rollback traps. That is not radical; it is practical compassion.
What follows matters beyond a single creek and one letterbox. Should counties create a fast-track process for non-commercial wildlife assistance on working land, they would safeguard habitat, voters and budgets at the same time. If they fail to do so, the message is straightforward: keep your gates closed. The hawk cannot read memos, and the fawn does not understand codes. People can do both. People can also create rules that welcome a stretcher at dawn rather than an unexpected bill at dusk.
| Key point | Detail | Why it matters to the reader |
|---|---|---|
| What triggered the bill | Land use was reclassified from agriculture to non-qualifying habitat management | Understand how a small change can produce a large tax bill |
| How to avoid the charge | Keep most acres in agricultural use, file a wildlife plan and speak to the assessor early | Practical measures to protect animals and your wallet |
| Why this becomes viral | It conflicts with the instinct to reward care rather than penalise it | Recognise the broader pattern behind local outrage |
FAQ:
- Where did this happen? The case described reflects several Midwestern and Southern counties where reassessments linked to habitat use have increased sharply.
- What is a “habitat-management tax”? It is not necessarily a separate tax, but rather a reclassification that removes favourable valuations, sometimes with multi-year rollbacks.
- Could a wildlife plan have prevented it? Often, yes, if the state recognises formal wildlife management as a qualifying use and the plan is filed before the activity starts.
- Is this the same as a commercial sanctuary? No. Non-commercial rescue work on operational land may be assessed differently from a paid attraction or permanent facility.
- How can readers help? Support local rescues with funding for permits and planning, and encourage counties to establish clear, rescue-friendly routes.
Comments
No comments yet. Be the first to comment!
Leave a Comment