
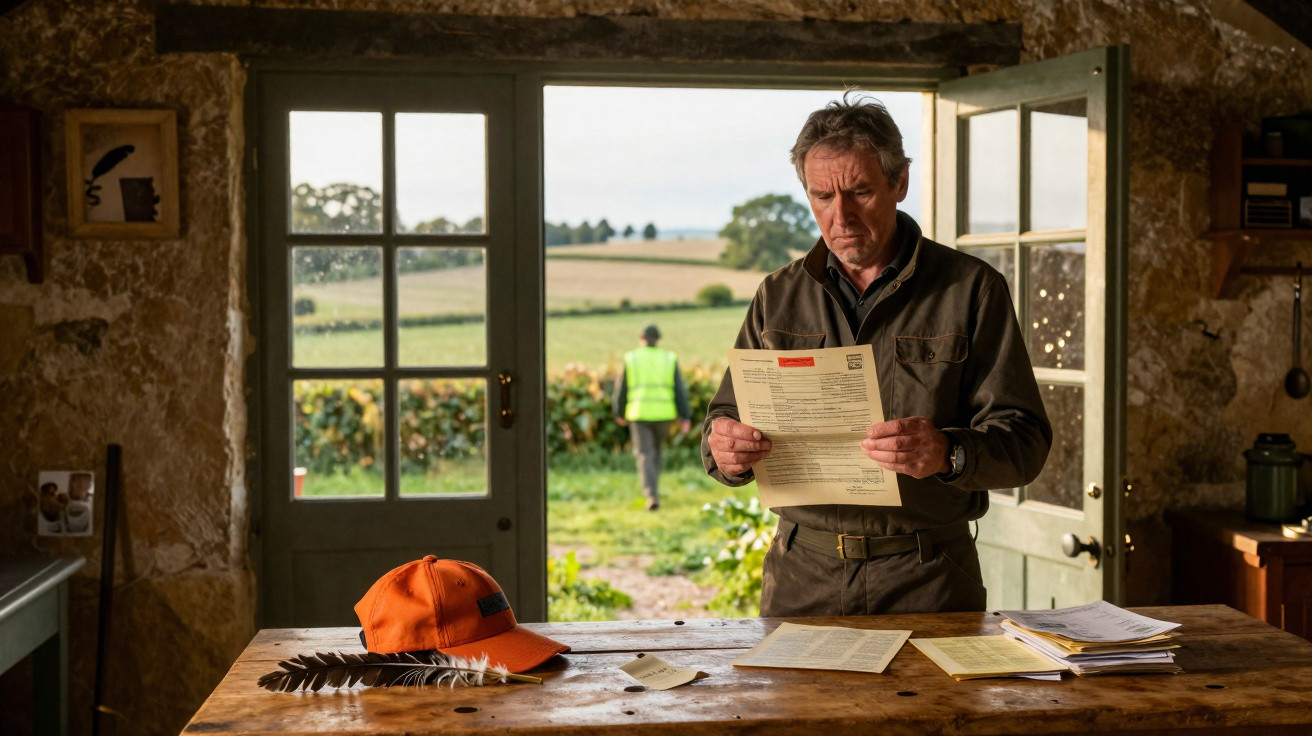
The farmer’s fields had an almost theatrical air that Sunday morning. Low mist still hung over the stubble, while the first gunshots echoed back from the hedgerows as orange-jacketed hunters made their way carefully across the land. Standing beside the track, his boots wet with dew, the owner looked on. He no longer farmed these hectares; the barn was half empty, and the tractor was used more to cut back brambles than to sow crops. Allowing the local hunting group onto the land seemed a modest way of keeping the place active. Of maintaining a connection with the village.
Then a brown envelope arrived.
It contained a demand for full agricultural tax. There was no exemption, no recognition of fallow land and no room for nuance. Just a figure that turned his stomach, followed by a tale that soon began circulating in the café.
This is where the countryside starts to disagree with itself.
When “doing a favour” becomes a tax bombshell
In theory, the situation appears straightforward. A landowner who is no longer truly cultivating his plots allows a local hunting association to use them during the season. There is no payment, no written lease, only a handshake and a gate key. To him, it is largely a social gesture: keeping paths open, limiting wild boar numbers and maintaining good relations in a village where everyone knows who owns each parcel.
But when the tax office checks the land register, one point stands out: land designated as agricultural is being used as hunting ground rather than being left fallow or restored for ecological purposes. In an instant, the “nearly abandoned” field is again regarded as a productive agricultural asset. That brings the full agricultural tax bill with it.
The account circulating in rural communities begins with a 68-year-old retired farmer who stopped growing cereals three years earlier. Costs had risen, there was no successor and his machinery was ageing. His fields remained, but there were no crops, no CAP payments and no revenue. Local hunters asked whether they could cross the land to reach a wood and put up several hides along the hedgerows. He agreed, even using his old tractor to help clear a track.
His annual tax notice contained a line that stunned him. The land had been reassessed as actively used farmland, meaning he lost the partial relief he believed still applied to “unexploited” or low-activity land. The difference amounted to almost a month of his modest pension. Friends in the pub said he had been “caught for helping out”. The story travelled quickly.
Once the emotion has faded, the reasoning behind this type of ruling is starkly simple. Tax officers do not ask, “Was he nice to the hunters?” They ask, “Is the land being used in a way that keeps it in productive rotation or retains its value?” If the answer appears to be yes, the field returns to the category of agricultural property taxable at the full rate.
There is a further issue. Hunting rights carry monetary value, even where no official rent is paid. Tax authorities may treat organised hunting, access routes or installed facilities as indirect commercial use. From their perspective, the land is not abandoned: it provides an advantage and retains market value. That may be enough to alter the tax position, whether or not the owner receives a penny.
How landowners can avoid the same agricultural tax trap
Behind the heated discussions in the café lies a quiet practical lesson. Anyone who owns land, even only a few hectares, should recognise that every “small arrangement” with neighbours can have legal consequences. This does not mean producing a 20-page agreement whenever someone crosses a field. It does mean recording who may use what, for how long and for which reason.
One straightforward approach recommended by some notaries is a brief, dated letter of authorisation stating clearly: “no rent paid, no commercial activity, no agricultural exploitation”. It takes ten minutes to prepare, costs nothing and can later demonstrate that the arrangement was social rather than economic in nature. It is not a guaranteed safeguard, but it provides a first line of defence if a tax inspector asks why lorries, dogs and guns are moving through an “unused” field.
The other real danger lies in the partly unspoken arrangements that feel so normal in rural areas. A local hunter leaves a trailer on a concrete pad “just for a few weeks”. A neighbour keeps three horses in a meadow “rather than letting it go wild”. A cousin grows sunflowers “just for the birds”. None of this seems like serious business. It feels like neighbours helping one another, as they always have.
Then, one day, administrative logic catches up and applies a label to what was thought to be simple goodwill. That label might be “agricultural exploitation”, “commercial lease” or “site used for leisure activity”, each carrying tax or legal obligations. We have all experienced that moment when a friendly favour abruptly resembles a legally risky arrangement that nobody anticipated.
Opinion in the countryside is sharply divided. Some argue that landowners must stop being naïve and manage their fields like any other asset. Others believe a system that penalises a man for allowing hunters to cross his land has lost touch with rural life.
“People in the cities want landscapes, game, open paths, but when a landowner lets that happen, he gets hit with the bill,” sighs a smallholder who recently turned down a hunting lease. “It makes you want to just close the gates and let the brambles take over.”
In discussions with notaries and farmers, three practical habits are repeatedly mentioned:
- Put at least the basics in writing, even where land is being used as a “friendly” favour.
- Seek professional advice on how land is classified and what might alter that classification.
- Decide whether hunting, grazing or access rights should be formalised through a token rent, or remain entirely informal but tightly limited in scope.
Caught between concern about the taxman and the wish to preserve rural goodwill, many owners feel they are walking a tightrope.
A countryside split between written rules and life on the ground
The story of a landowner “punished” for permitting hunters onto his fields highlights a deeper unease. It raises the question of who is entitled to decide what the countryside is for. Is farmland merely an entry in the cadastre, an asset category to be taxed and optimised? Or is it a living environment where relationships, favours and unspoken understandings matter as much as yield per hectare?
Some villagers quietly blame the hunters: “If you’d signed a small lease and declared everything cleanly, he might have had more clarity from the start.” Others fault the owner: “He should have updated his land status the day he stopped farming.” Some direct their criticism at the state, which promotes biodiversity and rural life while issuing tax demands that encourage people to fence everything off.
Between these three viewpoints, something valuable is at risk: the countryside’s ability to remain somewhat informal, without leaving landowners alone to face rules that seem designed for somebody else’s reality.
| Key point | Detail | Value for the reader |
|---|---|---|
| Land use changes the tax bill | Allowing organised hunting may be regarded as active use of agricultural land | Helps owners foresee when “simple favours” could result in full agricultural tax |
| Written records matter | Brief authorisations or agreements make the intended use and its nature clear | Provides readers with a practical way to limit disputes with tax authorities or neighbours |
| Ask before accepting | Check land classification with a notary or tax adviser before granting access | Lowers the chance of expensive surprises and protects fragile rural incomes |
FAQ:
- Question 1: Can allowing hunters onto my fields really alter my agricultural tax status?
- Question 2: Do I need a formal agreement with a hunting association to protect myself?
- Question 3: What happens if I earn no money at all from my land?
- Question 4: Who can tell me how my land is officially classified today?
- Question 5: Is it safer to deny all access and keep my land entirely closed?
Comments
No comments yet. Be the first to comment!
Leave a Comment