
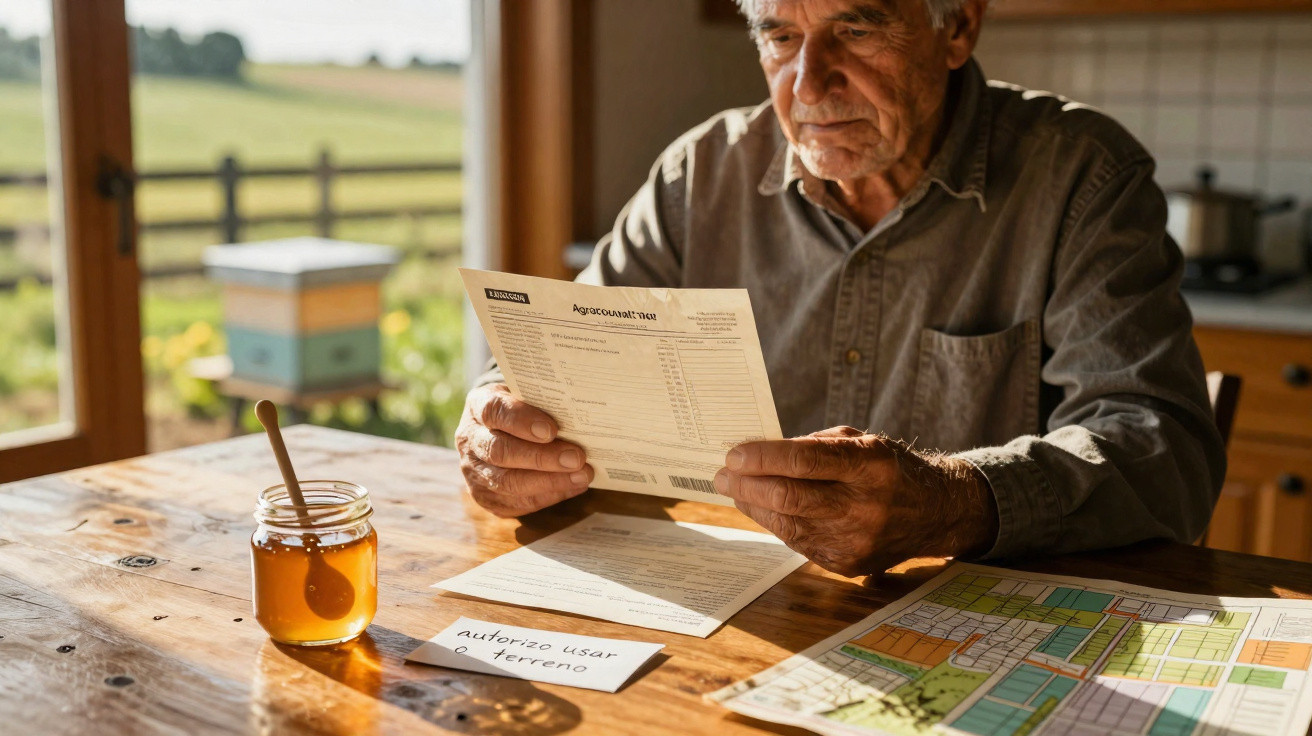
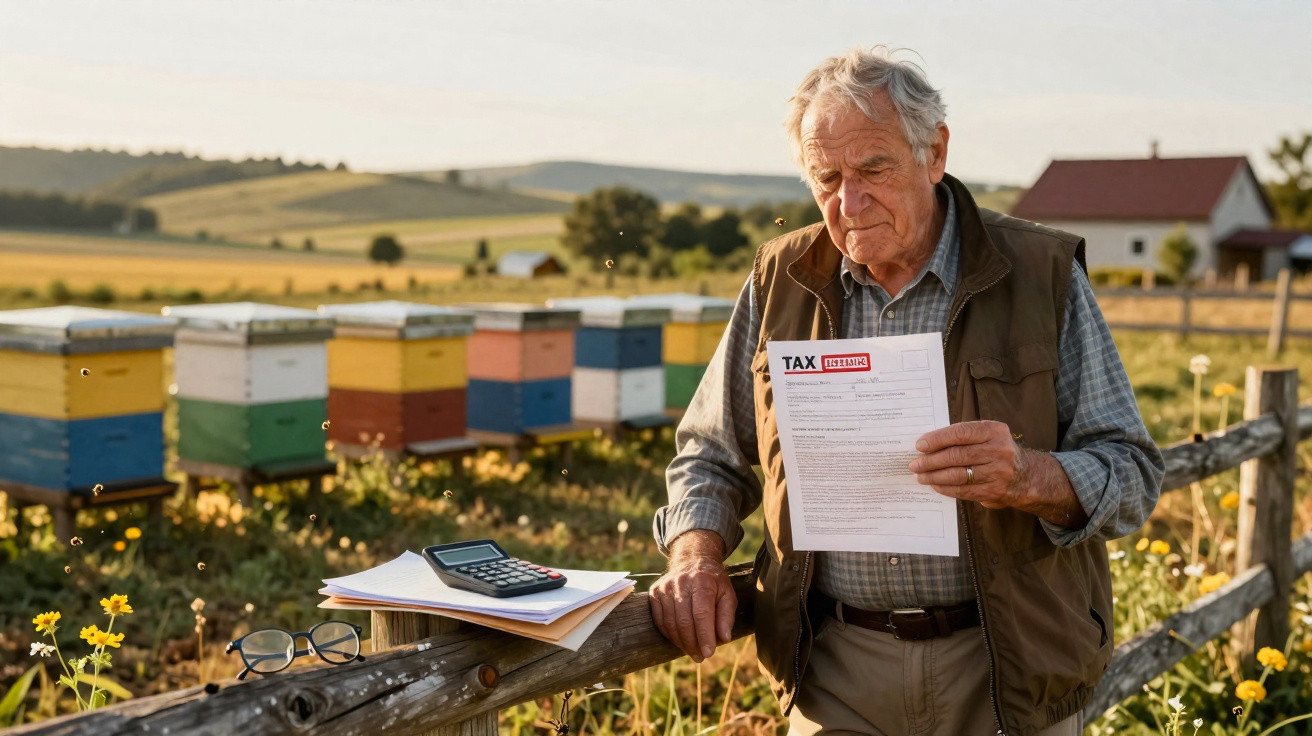
On a grey Tuesday morning, Gérard walks along the boundary of his field with his hands buried in his pockets. The air carries the subdued hum of thousands of bees. At the far end of the land, hives stand in orderly lines, painted pale blue and green by a beekeeper friend who could never have paid rent. For years, this patch of countryside has rested on an unspoken agreement: free room for the bees, a modest contribution to biodiversity, and no cash exchanged.
Now Gérard carries a letter in his jacket, folded and unfolded until the paper has worn thin. The tax office says he must pay agricultural levies. Not a handful of euros, but thousands. On land that, he insists, produces no income for him.
He looks towards the hives and says under his breath: “So this is what I get for being kind.”
Somewhere between the bees and the tax demand, a nation begins to argue with itself.
When goodwill meets the tax office
Like so many rural stories, this one started with a retired landowner, a beekeeper struggling to get by and a handshake. There was no lease, no rent and no paperwork, only mutual trust. Gérard owns several hectares that he no longer farms: the work of a lifetime now reduced to a modest pension against growing costs. A young beekeeper from the neighbouring village needs somewhere secure for his hives, away from roads and pesticides. The arrangement seems almost traditional, the kind of thing grandparents might have done without a second thought.
Then the tax paperwork arrives. Land that had never earned Gérard a cent is suddenly classified as being used for agriculture. Agricultural use brings agricultural levies. What began as a straightforward favour now comes with a bill.
The decision quickly became more than a local curiosity. After Gérard’s case appeared in regional news, radio phones rang across the country. Landowners called in to say, “That could be me.” Beekeepers shared images of their hives online, wondering whether the people hosting them would also receive bills. Comment sections filled rapidly.
Some people were appalled that anyone could be taxed on income they had never received. Others said the change was overdue, arguing that landowners had benefited from too many loopholes for too long. On discussion programmes, tax specialists and farming unions disputed the meaning of key terms: what qualifies as “use”? What counts as “income”? And who truly gains from these arrangements?
A low-key act of generosity had become a public test of fairness.
Underneath the outrage is a stubborn piece of legal reasoning. For tax authorities, the decisive issue is not whether payment was made, but the way the land is used. Fields made available for hives, grazing livestock or growing crops may automatically fall within agricultural rules. This can mean social contributions, possible VAT consequences and higher declared values, even where the owner says: “I never saw a euro.”
Tax officials maintain that organised land use may form part of an economic chain even without a formal rental payment. The beekeeper sells honey, while the hives occupy Gérard’s land as part of that trade. Viewed this way, the field is not inactive: it “works” for somebody.
Once land “works”, the system expects its share.
From neighbourly favour to taxable arrangement: what changes
For landowners following Gérard’s story with a sense of dread, the main lesson is clear: do not assume an informal favour is legally invisible. As soon as a plot is lent out, even without charge, it enters a framework of rules and definitions. A practical first step is a brief written agreement confirming that there is no rent, no agricultural profit and no commercial partnership. It may not automatically remove every levy, but it provides something tangible when the brown envelopes begin arriving.
Some owners now ask rural advisers or local notaries to examine these arrangements before a single hive is placed on the site. One short discussion in advance may prevent years of frustration later.
Most people in Gérard’s situation never set out to “optimise” anything. They simply hoped that an unused part of their land could help another person. That is why the reaction is so emotional. Beneath it lies a quiet worry: if generosity brings a tax cost, why should anyone continue to be generous?
The usual mistake is believing that “no income” means “no risk”. Tax rules are not built that way. In the calculation, use can matter more than money. When the brown envelope lands, panic often produces rushed and ineffective responses that worsen matters: angry letters, missed deadlines and incomplete forms.
Let’s be honest: nobody really reads the tax code before saying yes to a neighbour.
“It’s not about punishing kindness,” one senior tax inspector told a local paper, “it’s about treating similar situations in a similar way. If one landowner pays levies for agricultural use and another doesn’t, people stop trusting the system.”
- Set out the arrangement early
Record who will use the land, what it will be used for and the financial terms, even where those terms are zero. - Check local thresholds
Some areas apply minimum land-size or income thresholds that can alter your tax status overnight. - Keep evidence of your non-profit purpose
Save emails, messages or notes showing that the agreement is intended as environmental or social support rather than concealed profit. - Speak to an independent professional
A 30-minute conversation with a notary, accountant or rural adviser could prevent years of disputes. - Respond rather than blindly rebel
If you receive a levy, reply calmly, ask for the details and use the appeal process instead of ignoring the letter.
Retirement squeezed or loopholes closed?
The wider argument reaches beyond Gérard and even beyond bees. It strikes at a sensitive question: who pays for the countryside people say they want-green, thriving and full of biodiversity? When retired owners believe they are being penalised for offering a field to a beekeeper, they begin shutting gates, both literally and emotionally. No more hives, no shared orchards and no grazing for a neighbour’s sheep. The taxpayer inside them overtakes the neighbour.
Yet others have spent years seeing large estates use “friendly” arrangements to preserve land classifications that reduce their tax bills. To them, a firmer approach is not harshness but justice that has taken too long to arrive.
We have all experienced the point where a rule that sounds fair in principle appears cruel in reality. The tension in this case exists because both accounts can be true. Some people exploit loopholes, while others are sincerely trying to help. Tax codes rarely distinguish between them with the subtlety of village gossip. They operate through categories rather than feelings.
Clear rules often collide with complicated lives.
That does not make the debate futile. It means the real contest concerns where the boundary should sit, and who can move it when it cuts through everyday lives.
The discussion is now widening. Environmental organisations warn that if modest acts of generosity become financially hazardous, initiatives such as community apiaries and shared orchards may fade away. Farming unions fear that every reclassification could lead to higher contributions for people already under pressure. Campaigners for tax justice respond that, without consistency, the system becomes a collection of privileges for the well-connected.
Between those positions is a quiet majority of small landowners, watching and waiting. They wonder whether their next “yes” to a neighbour could quietly add a new levy to their bills. Some ask whether tax law should actively encourage ecological goodwill. Others ask whether good deeds should protect those who are discreetly gaming the system.
No algorithm can resolve that dispute. People alone can.
| Key point | Detail | Value for the reader |
|---|---|---|
| Goodwill may be taxable | Allowing land to be used, even free of charge, can trigger agricultural levies when it supports an economic activity. | Helps you identify possible hidden costs before agreeing to help a neighbour. |
| Paper is stronger than “gentleman’s deals” | A straightforward written agreement and basic professional guidance can affect how authorities assess your circumstances. | Gives you ways to safeguard your retirement and prevent unpleasant surprises. |
| The debate extends beyond one case | The dispute exposes conflict between tax justice, rural survival and ecological goodwill. | Encourages you to form a view and contribute informed opinions to the continuing public debate. |
FAQ:
- Question 1 Can I genuinely be taxed for letting a beekeeper use my land without charging rent?
- Question 2 What written agreement should I put in place before lending out my field?
- Question 3 Can environmental uses, such as keeping hives, ever lower taxes rather than raise them?
- Question 4 What steps can I take if I receive an unexpected agricultural levy demand?
- Question 5 Could this form of taxation be extended to other informal rural arrangements?
Comments
No comments yet. Be the first to comment!
Leave a Comment