
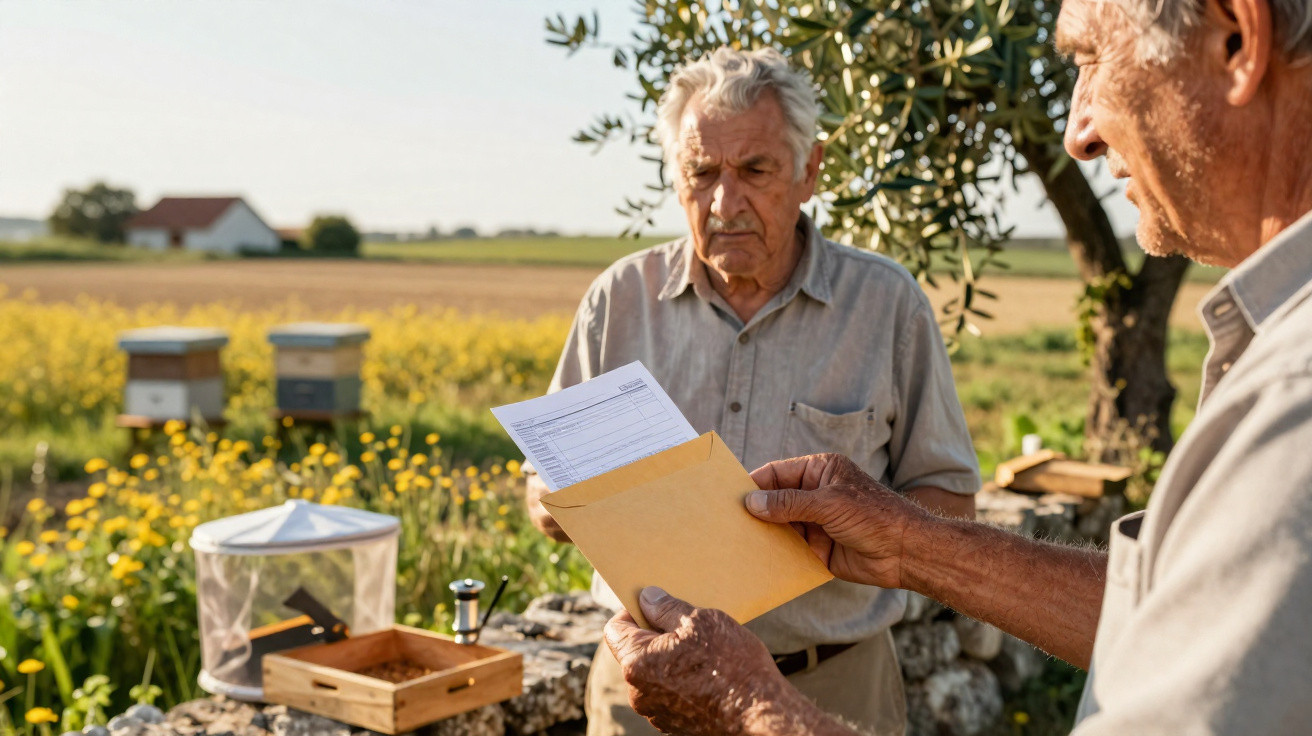
A peaceful corner of his property, several wooden hives and a young beekeeper thankful for somewhere to set up. There was no rent and no written agreement: only a handshake and bees humming above the wildflowers. Then a letter landed on his doorstep. It was not a thank-you note or a pot of honey, but a tax demand.
He looked at the figure, his pulse quickening. The notice referred to agricultural tax for “productive land use”. It concerned income he had never received, work he had not undertaken and a business that was not his. Yet, in official records, his retirement retreat had turned into a miniature farm.
People across the country soon began to debate the case. Had he been gullible? Were the regulations unjust? Or had the beekeeper quietly passed the liability on to him? A single line in the letter altered the whole picture.
When a kind gesture becomes a beekeeping tax nightmare
Like many arrangements in small towns, the retiree’s situation started with a friendly conversation over a fence. The beekeeper was looking for land, while the retiree had an unused strip available. It seemed innocent, even idyllic - bees, wildlife and community-minded cooperation. He welcomed the thought that his ground could support the pollination of local orchards.
He had not expected the tax authority to regard that same strip as an agricultural asset. There was no business plan, no sales and no honey income entering his bank account. Nevertheless, the official paperwork showed that the land had passed an unseen boundary, moving from “private property” to “agricultural use”. On the other side of that boundary was a tax bill.
People in the area say he was shocked. He had spent his working life meeting his obligations before retiring to a modest home that was finally his own. He saw the hives as a pleasant addition, not an expense-generating enterprise. Overnight, a generous gesture had become a legal category, and the state sought its portion.
The social-media reaction was immediate and fierce. Some commenters viewed him as the casualty of an inflexible system, while others said he had been careless. News articles appeared, television discussion programmes took up the case, and the retiree’s quiet field became the focus of a nationwide argument. The issue was no longer simply bees, but where responsibility begins and where it ends.
From a practical perspective, the tax authority’s reasoning was straightforward: the hives formed part of an agricultural activity conducted on his land. Even if he had not sold one drop of honey, an economic use of the land existed. The beekeeper generated income there, and the owner was legally connected to that use. Personal motives were irrelevant to the system; the recorded use of the land was what mattered.
That is the hard reasoning behind many tax regulations. They do not consider who had good intentions; they consider who owns the asset. For this retiree, that meant entering a complicated world of agricultural classifications and property definitions he had never realised existed. He saw flowers, while the authorities saw a taxable unit.
How to lend land without sacrificing your peace of mind
For landowners tempted to “just help” a farmer or beekeeper, the simplest and most valuable safeguard is to put the arrangement in writing. A brief, unambiguous land-use agreement can separate your goodwill from another person’s business activity. It need not resemble a 40-page legal document: two pages may be enough to make all the difference.
The agreement should identify who is liable for each matter, including taxes, insurance, liability and registration. It should confirm that the beekeeper operates independently, at their own expense and risk. Include a nominal rent, however small, paid through a bank transfer. That modest payment can demonstrate the existence of a genuine lease rather than an informal business partnership.
It is also sensible to speak to a local tax adviser before a first hive, tractor or greenhouse appears on your land. A short consultation can explain your property’s classification and the consequences of agricultural activity beginning there. It may seem tedious, certainly, but it is far less painful than learning the rules through an unexpected demand for payment.
Many people fall into the blurred space between friendship and legal responsibility. They let a relative, neighbour or young farmer use land while they establish themselves. Raising contracts and tax liabilities can feel unkind when the arrangement was intended as a favour. You may not wish to “formalise” something that was meant to be informal.
Yet this is precisely how discreet favours become major problems. Once a dispute occurs, or the tax authority identifies activity through satellite imagery or registry records, no one can recall who agreed to what. The landowner is almost always the easiest person to pursue. At worst, that can involve tax reassessments, penalties and even legal difficulties if something goes wrong on the property.
It is painful on a personal level. You assist somebody, only for the state to treat you as their commercial partner. The beekeeper in this case may not have intended to leave a retiree with the bill. Still, silence, imprecise arrangements and “we’ll figure it out later” can produce exactly that result. We all love the idea of community, until bureaucracy walks in with receipts.
An agricultural solicitor who had followed a comparable case put it bluntly:
“When money is being made on someone’s land, the tax man looks at the landowner first. If you don’t shift the risk on paper, you carry it by default.”
There is a further lesson from the beekeeper’s perspective: land provided free of charge is rarely genuinely free. When an activity depends on somebody else’s property, the operator must protect the owner as well as themselves. This may involve taking out liability insurance in their own name, registering the business correctly and formally accepting that taxes arising from their activity are theirs rather than the retiree’s.
- Record every land-use arrangement in writing, including those involving family members.
- State clearly which party pays each tax.
- Retain evidence of lease payments, however small they may be.
- Seek basic legal or tax advice before hives or crops are introduced.
- Check your land’s classification annually, particularly following changes.
Who is truly responsible when the rules seem unfair?
The compelling and uncomfortable element of this story is that nobody appears entirely blameless, but nobody seems wholly at fault either. The retiree was not acting maliciously; he was simply trusting. The beekeeper was probably trying to survive in a difficult market, searching for any available free plot to reduce costs. As for the tax authority, it applied the rules available to it.
The country consequently split into opposing camps. Some considered the retiree further proof that rigid systems punish kindness and prioritise paperwork over people. Others maintained that ownership carries obligations, and that not knowing tax law does not remove them. A smaller number blamed the beekeeper, claiming they had taken advantage of an older man’s goodwill.
Between these views sits an awkward reality: modern legal systems are no longer designed for handshake arrangements. They do not “see” generosity or intention. Instead, they register use, ownership, activity and liability. That leaves many older landowners vulnerable, particularly those raised in a time when a firm handshake carried more weight than a PDF.
Social-media comments beneath the story often reveal more about people than they do about bees or taxation. They show anger towards institutions, but also irritation with an education system that does not teach basic property law. One commenter wrote, “We spend years learning algebra we never use, but nobody tells us a single thing about tax law that can ruin our lives in ten minutes.” It is difficult to disagree.
A quieter issue also runs through the debate: should small-scale environmentally beneficial activities, such as beekeeping, face more flexible rules when they take place on someone else’s land? Environmental campaigners say they should. They argue that pollinators, community gardens and small agricultural projects deserve lighter regulation. Many readers agree, picturing their own unused plots as potential green refuges.
Tax authorities are concerned about the reverse outcome. They see potential loopholes, with people disguising substantial businesses behind “eco” labels. The dividing line therefore remains strict. Land used for production is subject to the same tax logic, whether it contains ten hives or ten hectares. Ordinary people then find themselves caught on that boundary, asking when a favour became a taxable event.
In some respects, this retiree’s bad luck is a reflection of modern life. It shows how far everyday experience has moved away from the rules that govern it. On a summer afternoon, bees and wildflowers appear harmless. On a tax return, they may be treated as commercial activity. Somewhere between those two perspectives, real people with genuine fears about money and security are attempting to keep their balance.
That may be why the story continues to circulate in the news. It reaches beyond a straightforward disagreement over a tax demand. It concerns trust, the price of generosity in a heavily regulated world and the persistent fear that a seemingly minor choice - lending a field or signing a document - could return years later with an official seal and a request for money.
| Key point | Detail | Why it matters to readers |
|---|---|---|
| Hidden tax risks for landowners | Even land lent “free” for beekeeping or farming may trigger agricultural tax | Helps you identify risks before agreeing to help a neighbour or relative |
| The value of simple contracts | Brief written agreements can transfer tax and legal responsibility to the person actually running the activity | Offers a practical way to protect your retirement income or savings |
| Blame versus system failings | The dispute exposes the divide between good intentions and rigid property rules | Encourages you to reconsider how you handle favours, land and bureaucracy |
FAQ:
- Did the retiree really have to pay if he made no profit? The tax depends on the land’s classification and use, rather than solely on the owner’s personal profit. If the land is used for agricultural activity, the owner may still be taxed despite receiving no direct income.
- Could a simple written agreement have protected him? In many jurisdictions, yes. A clear lease or land-use agreement can establish that the beekeeper operates independently and is responsible for the related taxes and obligations.
- Is the beekeeper legally at fault in cases like this? Not necessarily. They may have complied with every rule governing their own business while the land classification still affects the owner. Opinions differ sharply on their moral responsibility.
- What can I do before letting someone use my land? Speak to a local tax or legal adviser, prepare a straightforward agreement and check how your land is registered. Let’s be honest: nobody really does this every day, but one short meeting can prevent years of stress.
- Are these tax rules the same in every country? No. Every country - and sometimes every region - defines agricultural use and land tax differently. The story has relevance across borders, however: informal favours frequently clash with formal systems.
Comments
No comments yet. Be the first to comment!
Leave a Comment