
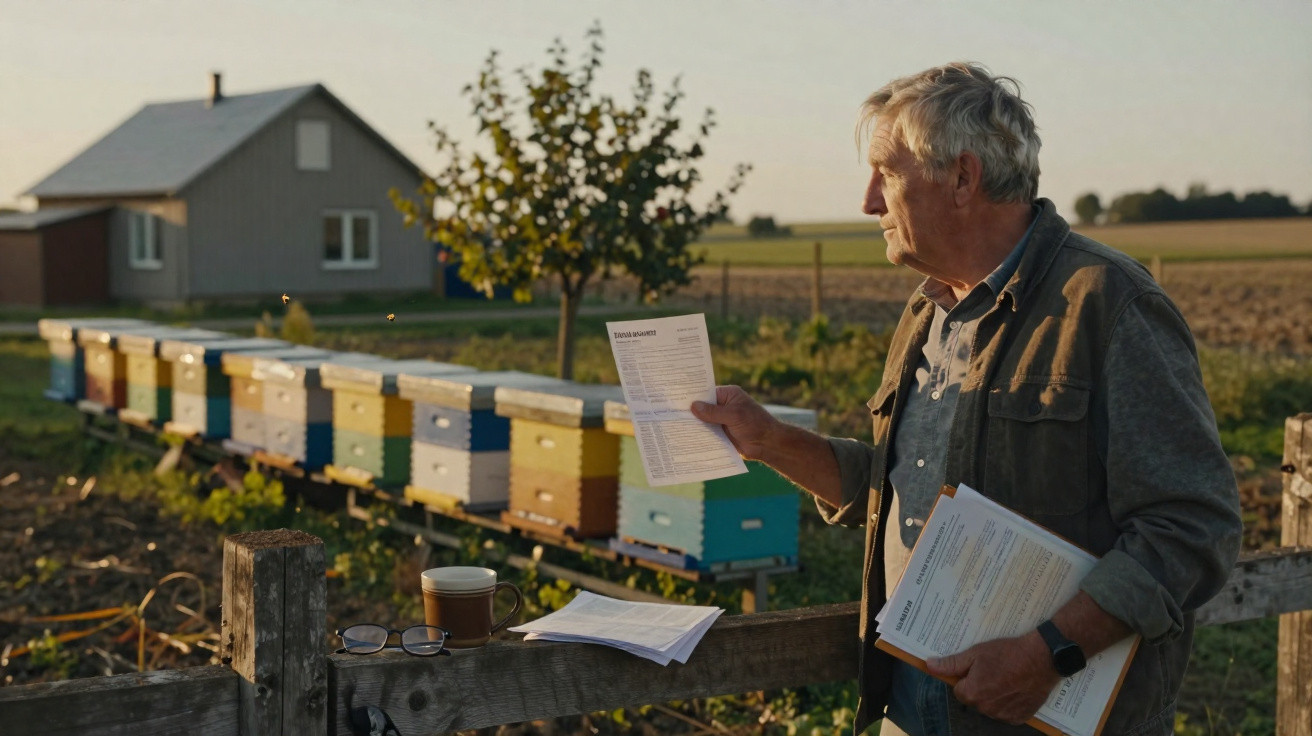
A strip of unused land, a handful of thistles and a fence tilting to one side: that was all it seemed to be. Yet, behind a line of poplars, fifty colourful wooden hives buzzed softly in the afternoon warmth. The beekeeper’s van had already driven away. Only the bees, and a slight scent of smoke, were left.
For months, this had seemed like a modest miracle during a peaceful retirement. The arrangement between neighbours was straightforward: the hives could occupy the space for free, honey would be given in return, and everyone could feel they were helping the planet. Then a tax letter arrived through the door: a heavy envelope, an official crest and wording that appears harmless until you see the figure at the bottom.
A good deed had brought an unpleasant surprise. One kind gesture had been reclassified as agriculture. In the eyes of the tax office, agriculture carries a charge.
When a favour becomes a “farm” on paper
The retired man, a former engineer in his late sixties, believed his complicated paperwork ended when he handed in his final office pass. He owns a quiet plot at the edge of town: too small to grow crops and too overgrown to build on. When a local beekeeper asked whether a few hives could be kept there, his reply was immediate: “Of course, why not?” To him, it was no different from lending a neighbour a ladder or lawnmower.
There was no formal agreement and no payment. There were only bees, wooden boxes and the occasional jar of honey left at the gate.
Several months later, however, the tax inspector interpreted the situation very differently. Satellite photographs and registry records showed that the land was no longer “unused”. An activity was taking place and honey was being produced. Under a strict interpretation of the rules, that meant agricultural use. In many areas, agricultural use moves land into another tax band, with rates that can hurt more than a bee sting.
Similar accounts are beginning to appear on rural forums and local Facebook groups. A retired teacher in the Midlands found that her “wildflower corner” was being treated as part of a commercial beekeeping operation after a friend’s hives had remained there for three consecutive summers. In the US Midwest, a family had their property flagged after allowing hives beside their pond, which led to a reassessment by the county assessor.
These are not large farms or corporate land transactions. They are informal, neighbourly arrangements that resemble exchanging tomatoes across a fence far more than operating a business. On paper, however, they may cross unseen boundaries. In certain jurisdictions, the repeated production of food products on land - even where the work is carried out by somebody else - can place it in an agricultural classification. Depending on the system, the change may lead to higher or lower taxes, but it nearly always creates additional bureaucracy.
Tax lawyers say the trend is unmistakable. As authorities increasingly rely on satellite imagery, cross-referenced databases and automated risk alerts, supposedly informal land use becomes easier to identify. A row of hives ignored ten years ago may now prompt an algorithmic warning. Once the system identifies the property, the responsibility can shift to the owner, who must show that they are not a small-scale farmer liable for a new tax.
How to support bees without risking an agricultural tax bill
It is possible to offer land without turning a calm retirement into a tax dispute, but the preparation should begin before the first hive is delivered. Treat it as you would letting someone park a van on your drive: it may be a friendly arrangement, but a few boundaries still matter. A brief written note or email confirming that the beekeeper operates independently, that no rent is paid and that the land remains non-commercial for the owner can be helpful.
In some places, part of a property can also be declared a “conservation”, “wildlife” or “non-productive” area, even where bees visit it. This may preserve the owner’s status as a private individual rather than a farm. Before any hives are installed, a fifteen-minute discussion with a local tax adviser or land registry office will often cost less than one unexpected tax demand.
It may sound tedious, but it is how a generous act is rooted in practical reality rather than good intentions alone.
Many landowners avoid asking straightforward questions because they feel impolite. After all, who wants to quiz a friendly beekeeper with a gentle manner and jars of golden honey? But staying silent can have consequences. Without knowing whether the beekeeper is registered as a business, sells honey or uses the property’s address for their operation, the landowner enters the arrangement without a clear view of the risks.
Let us be honest: nobody really does this every day.
Still, one brief discussion may prevent months of worry. You could politely ask: “Are my details anywhere on your business registration or labels?” and “If the tax office calls, who do you say is running the beekeeping activity?” Many beekeepers are as keen to avoid tax difficulties as landowners are. Some will readily sign a short declaration confirming that the hives belong to them, the business is theirs and the landowner merely provides space without receiving a share of the profits. When the rules become unclear, that one sentence can make a difference.
For some retired people, the emotional impact is as significant as the bill itself. They feel penalised for attempting to do something positive. One landowner put it this way:
“I planted trees, left the grass long for insects, then welcomed the hives because everyone keeps saying ‘save the bees’. The next thing I know, I’m getting treated like a farm that forgot to pay its dues.”
Beneath that frustration is a quieter concern: if a small generous gesture can create this problem, what other things might we be getting “wrong” without realising it? Practical measures can offer some reassurance:
- Ask your local tax office how it classifies land used for another person’s hives, and ask for its response in writing.
- Keep photographs and records of dates, including when the hives arrived, who installed them and any written correspondence.
- Include unambiguous terms in any agreement: “no rent”, “no agricultural activity by the owner”, “no share of honey profits”.
- Check your property tax statement annually for an unexpected change of category.
- If the issue has already arisen, speak to a local ombudsman or taxpayer advocacy group before making payment.
A quiet conflict between climate virtue and tax reality
This situation exposes an awkward contradiction. Governments encourage people to protect biodiversity, assist pollinators and make better use of idle land. Yet those same governments often administer tax rules created for a world of clearly defined farms and factories, rather than blurred combinations of hobbies, environmental action and neighbourly favours. The retired person with hives at the end of a field falls directly into that gap.
On a personal level, the figure is familiar. It is someone who spent their working life following the rules, finally has some time and space, and chooses to undertake a small “good deed” project. Hosting beehives appears almost symbolic: quiet, useful and environmentally friendly. When a brown envelope then recasts that act as taxable activity, the impact goes beyond money. It can feel as though the system is saying that trusting others - and trusting it - was naïve.
From a legal perspective, however, the system is performing the function it was designed for: classification, categorisation and standardisation. A hive is a production unit. A production unit on land is agriculture. Agriculture belongs in a particular category. That category has a rate. The software has no search field for kindness.
Some countries have begun to adjust their approach. A small number of European regions, for example, are considering specific exemptions for the “micro-use” of private land for environmental aims, including small groups of hives, bat boxes or ponds. The principle is straightforward: provided the landowner receives no rent and does not directly sell products, the property remains in its original tax category. There is an environmental benefit, without a fiscal penalty.
Rules change slowly, though, and bureaucracy seldom moves as quickly as climate anxiety or local goodwill. Until that divide becomes narrower, cases involving retired landowners presented with agricultural tax bills will continue to emerge. They serve as warnings, but also as invitations: invitations to speak with neighbours who keep hives, local councils and tax offices before the bees arrive; and invitations to reconsider how society values the quiet, unpaid work of sharing space with the living world.
Everyone knows the moment when an uncomplicated favour abruptly becomes difficult. It is tempting to withdraw, shut the gate and tell the beekeeper to look for another field. But another option exists: people can still agree to small acts of generosity while supporting them with paperwork, advice and collective pressure to modernise outdated rules. That route is less simple. It may require questions, signatures and perhaps even local campaigns.
Yet, if landscapes are to hum with more than lawnmowers and traffic, that complexity may be the cost of progress. This time, the cost is not measured in euros or dollars, but in conversations people never expected to need. The retired owner at the edge of town may not have chosen to be part of that discussion. Nevertheless, the story spreads quickly, passing from neighbour to neighbour and article to article, like a swarm searching for a new home.
| Key point | Detail | Why it matters to the reader |
|---|---|---|
| Hidden tax trigger | Lending land for hives can reclassify property as “agricultural” in some systems | Helps you recognise when a good deed may have tax consequences |
| Paper protection | Simple written agreements and local tax advice can establish that the activity belongs to the beekeeper | Provides practical ways to protect yourself without refusing to host bees |
| Policy gap | Environmentally friendly land uses often clash with outdated tax classifications | Encourages you to question, and if necessary challenge, how your land is categorised |
FAQ:
- Can lending my land for beehives really change my tax status? In some jurisdictions, yes. Regular food production on your land, even where it is carried out by another person, can move it into an agricultural category and trigger a reassessment.
- Does it matter if I don’t get any money for the hives? Not in every case. Receiving no rent supports your position, but authorities may consider the actual use of the land rather than financial benefit alone.
- What simple steps can I take before hosting hives? Obtain a short written agreement, ask how the beekeeper is registered and check with your local tax office how this type of use is classified in your area.
- Can I reverse a tax reclassification once it happens? It is often possible to appeal or request a review, especially if you can demonstrate that you are not involved in the beekeeping business and did not profit from it.
- Is there a way to help bees without touching my tax profile? You could plant pollinator-friendly flowers, provide financial support to local beekeepers or host educational events, without turning your land into a production site.
Comments
No comments yet. Be the first to comment!
Leave a Comment